Four days after my C-section, my mother-in-law called and snapped, “Even if you have to crawl, come here and help this family.”
PART 2
I called my former supervising attorney, Frances Osei, that same evening, despite Josephine's gentle protest that I should be resting rather than working the phone four days post-surgery.
"I need you to look at something," I told her, forwarding the credit alerts, the vendor invoice, and the personal guarantee document bearing a signature that wasn't mine. "I think my mother-in-law forged my signature, and possibly my mother's, on a business loan."
Frances called back within the hour, her tone considerably more serious than I'd anticipated. "This isn't a gray area, Alexandra. The signature on this guarantee doesn't match any exemplar I've seen from you, and the notarization stamp attached to it belongs to a notary who, according to the state registry, had her commission suspended eight months ago for exactly this kind of irregularity. This looks like straightforward loan fraud, and given the amount, it's well past the threshold for felony charges."
"What about my mother's name on the second guarantee?"
"Same pattern, presumably. I'd want to see the actual document to confirm, but if it matches this one, we're looking at fraud against two separate victims, potentially compounded by whatever your mother-in-law told the lender about both of your financial standing to secure approval in the first place."
Josephine, listening from the doorway of my recovery room, went very quiet once she understood the scope of what Frances was describing. "She used my name too? I've never even co-signed anything for that family."
"Exactly," Frances said. "Which is going to matter considerably once we bring in law enforcement rather than simply pursuing this as a civil matter."
We spent that evening compiling everything I already had access to from my months of quietly reviewing the catering company's books—invoices, the original loan application, correspondence between Marlene and the lender that, buried in an old email thread I'd been copied on months earlier for an unrelated bookkeeping question, explicitly referenced "using Alexandra's excellent credit profile" to help secure more favorable loan terms.
"She planned this," I said, reading that email for what felt like the tenth time. "This wasn't some panicked, last-minute decision. She specifically targeted my credit profile because she knew it was strong enough to get the loan approved."
PART 3
Frances filed a formal fraud complaint with the district attorney's office the following morning, alongside an emergency civil filing seeking immediate release of liability for both Josephine and myself from the loan guarantee, given the clear evidence of forgery.
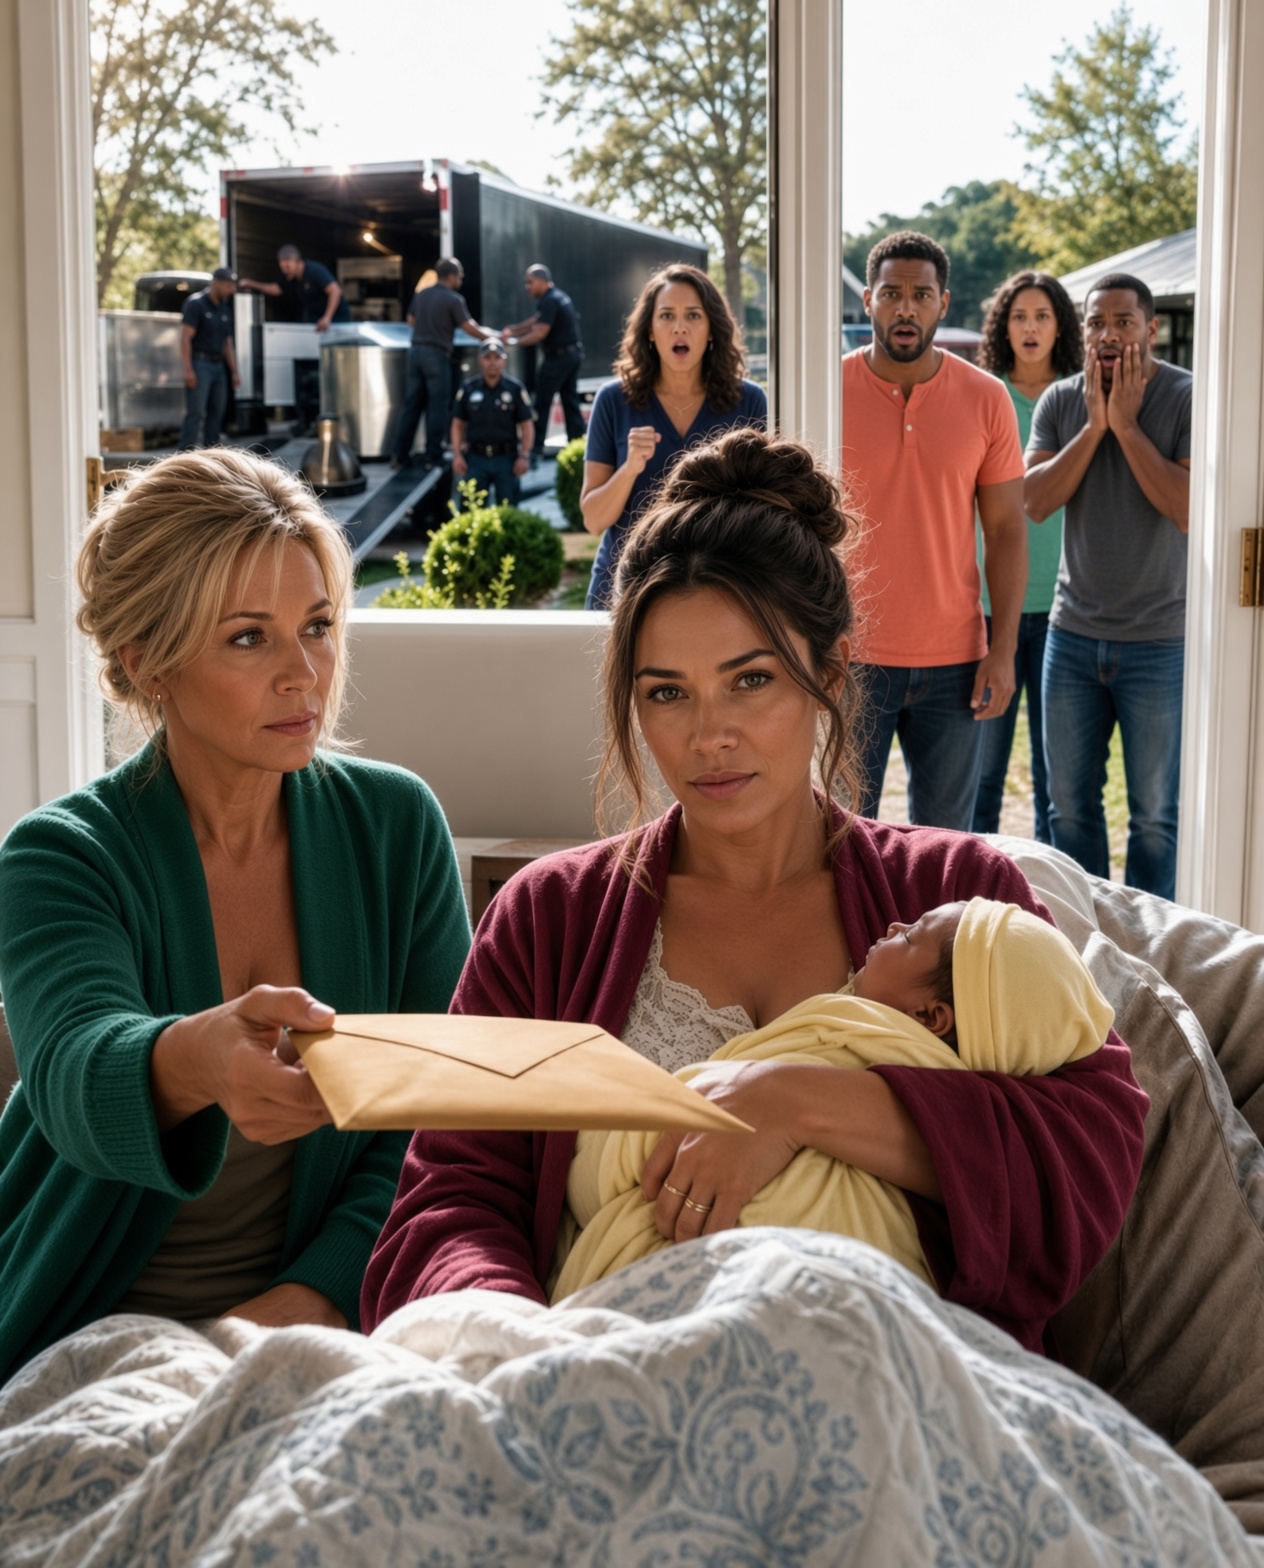
The "three black trucks" that appeared on Marlene's lawn the next morning, the ones that left her standing barefoot in shock according to the account Curtis later gave me, belonged to the lender's asset recovery team, dispatched once Frances's filing triggered an emergency review of the loan's underlying collateral documentation. Once the bank's own compliance department discovered the forged guarantor signatures, they moved immediately to begin recovery proceedings against the catering company's equipment and receivables, the actual assets that had originally secured the loan, now that the fraudulently obtained guarantees could no longer be relied upon to backstop the debt.
The court officer accompanying the recovery team served formal notice of the emergency civil filing, along with a temporary restraining order preventing Marlene from any further use of my name or Josephine's on any financial documentation pending the fraud investigation's conclusion.
Curtis called me in a panic within the hour. "Alexandra, what did you do? There are trucks here. They're taking the ovens. Mom is losing her mind."
"I didn't do anything except tell my attorney the truth," I said. "Your mother forged my signature and my mother's signature on a business loan for a hundred and eighty-six thousand dollars. That's not something I created, Curtis. That's something she did, months ago, apparently confident neither of us would ever notice."
"She said it was just a formality. That she'd handle the payments herself and we'd never even need to know."
"Did you know about this before yesterday?"
A long silence. "I knew Mom mentioned needing a loan for new equipment. I didn't know she'd used our names without asking."
"But you suspected something, Curtis. I saw your face yesterday when I asked. That's not the reaction of someone hearing about this for the first time."
He didn't have a response for that.
PART 4
The following weeks brought a slow, uncomfortable unraveling of exactly how much Curtis had actually known, and for how long. Frances's investigation, combined with the bank's own internal review, established that Curtis had co-signed an earlier, smaller loan for the catering business eighteen months prior, one that had gone into default, prompting Marlene's decision to seek the larger, fraudulently guaranteed loan specifically to consolidate and cover the earlier default before it damaged the family's credit further.
Curtis hadn't known about the forged signatures specifically. But he had known, for months, that his mother was managing the business's finances in increasingly desperate and questionable ways, and had chosen not to mention any of it to me, despite my growing, unpaid role handling much of the company's actual bookkeeping.
"You let me keep fixing her books," I told him, during one of several painful conversations that followed, "without ever once mentioning that the underlying finances were built on a foundation you already suspected was unstable."
"I didn't want to worry you during the pregnancy."
"I found out about a hundred and eighty-six-thousand-dollar fraud four days after major surgery, Curtis. 'Not worrying me' is not what happened here."
Marlene, facing formal fraud charges alongside the civil liability, initially attempted to characterize the forged guarantees as a misunderstanding, insisting she'd had "verbal permission" from both Josephine and me to use our names—a claim that collapsed immediately once Frances produced the email explicitly discussing using my "credit profile" without ever mentioning any actual conversation with me about it.
The criminal case concluded with Marlene accepting a plea deal: felony fraud charges reduced in exchange for full restitution and probation, given her age and lack of prior criminal history, though the civil judgment released both Josephine and me from any liability on the loan and awarded damages covering our legal fees and the credit damage the fraudulent guarantee had caused before we discovered it.
PART 5
It's been sixteen months since that Sunday phone call.
Curtis and I separated four months after everything came to light, not immediately, but gradually, as it became clear that rebuilding trust after months of him quietly enabling his mother's financial desperation at my expense required more honesty and accountability than he was consistently able to offer. Our divorce, finalized last month, was amicable regarding custody of Sage, though considerably less so regarding the broader questions of trust that the fraud had permanently damaged.
Marlene's catering business didn't survive the asset recovery and subsequent legal proceedings. She's since taken a bookkeeping position at a much smaller company, one where, according to Curtis, she's required considerably more oversight than she was ever willing to accept as the head of her own business.
Josephine and I have grown closer through the entire ordeal, an unexpected silver lining given how directly her own name had been dragged into Marlene's scheme alongside mine. She moved into a small guest suite in my new house for the first several months after the divorce, an arrangement that started as practical support during an exhausting transition and has, gradually, become something we both genuinely enjoy maintaining even now that I'm considerably more settled.
Sage just turned one. She has no memory, of course, of the chaotic first weeks of her life, the forged signatures, the black trucks on her grandmother's lawn, the slow unraveling of her parents' marriage that followed close behind. I intend to make sure her actual memories of that grandmother, going forward, involve considerably more honesty and considerably less financial manipulation than the foundation Marlene tried to build without either of us knowing.
I returned to paralegal work six months ago, part-time initially, now full-time at Frances's firm, bringing with me a level of personal, hard-won understanding of fraud investigation that, strangely, has made me considerably better at the work than I was before any of this happened.
I think about that phone call often—Marlene's cruel, dismissive laugh, Curtis's failure to defend me, my own mother's calm, immediate refusal on my behalf. I've come to understand that single sentence, "My daughter isn't going anywhere," wasn't simply protective in the moment. It was the first small crack in a family dynamic that, once properly examined, revealed considerably more rot underneath than any of us initially understood.
I didn't crawl to that Sunday lunch, four days after major surgery, the way Marlene demanded. Instead, I built the case that ended her business, exposed her fraud, and finally, permanently, established exactly whose name would never again be used without genuine, informed consent.
THE END
For 12 Years My Stepdaughter Returned Every Gift—Then One Box Revealed Her Father Had Been Lying to Us Both
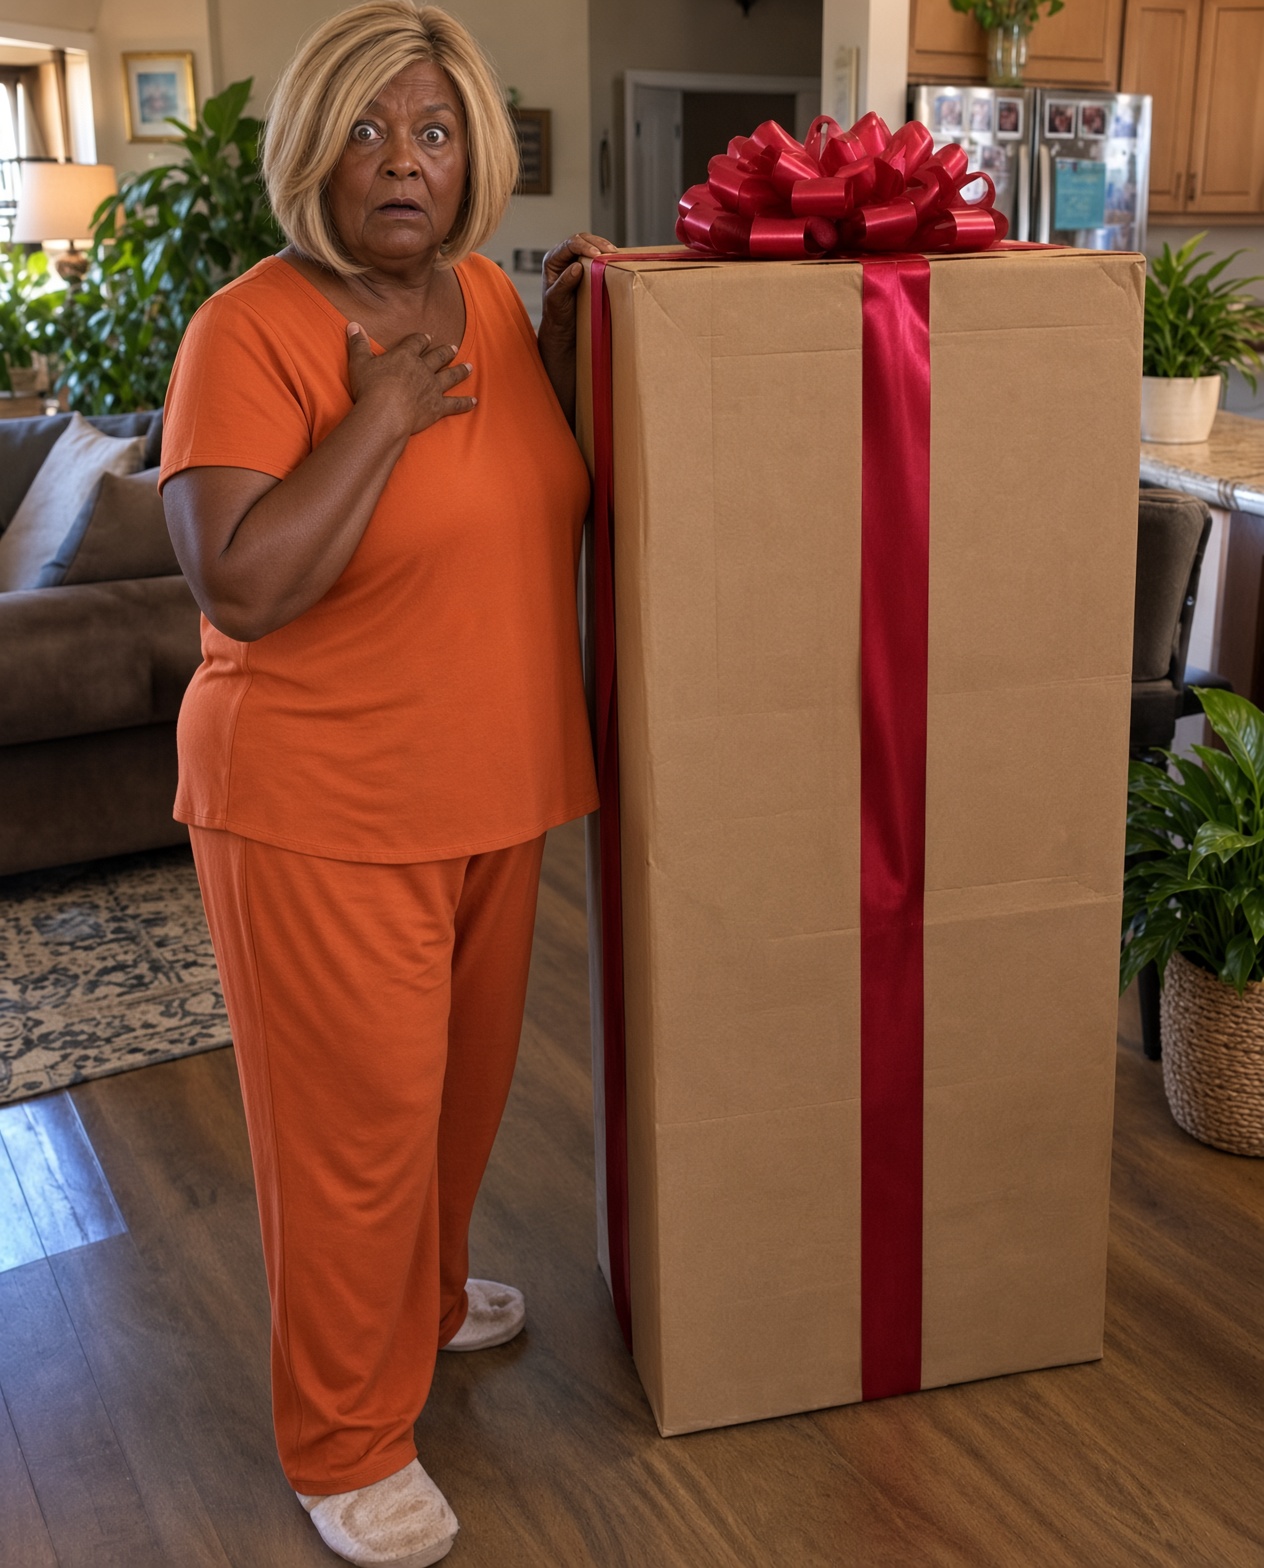
The first thing inside the box was a stack of unopened birthday packages.
My packages.
All twelve of them.
Every label.
Every ribbon.
Every RETURN TO SENDER sticker.
Except something was wrong.
The return stickers had been placed over the original tracking labels.
And beneath several of them, in faded ink, was my own address.
I stared.
“Mark.”
He said nothing.
I picked up the package from Sophie’s eighteenth birthday.
The delicate necklace.
Still wrapped in the same silver paper I remembered.
The postal sticker showed it had never reached Sophie’s college address.
It had been intercepted and redirected back from our own town.
I looked at Mark.
“What is this?”
His mouth opened.
Then closed.
Under the packages were printed emails.
Hundreds.
Some from me to Sophie.
Some from Sophie to me.
Except I had never seen hers.
The first one was dated two weeks after she left for college.
Helen,
I’m sorry I left without saying goodbye properly.
Dad says you’re angry with me and think I ruined the wedding year for both of you.
I don’t know what I did.
I know you tried.
I just need space from him right now.
Please don’t think I hate you.
My stomach dropped.
I turned the page.
Another email.
Then another.
Sophie asking whether I had received her Christmas card.
Sophie asking whether I wanted to visit campus.
Sophie apologizing after Mark told her I had said, “If she doesn’t want to be family, I’m done chasing her.”
I had never said that.
Not once.
“Mark.”
He stood.
“Helen, let me explain.”
“No.”
I kept reading.
The emails stretched across years.
At nineteen, Sophie wrote:
Dad says you don’t want me contacting you directly because it puts you in the middle.
I don’t understand what middle I’m supposed to be in.
At twenty-one:
I got the handbag.
Dad said you only sent it because he reminded you.
I still wanted to say thank you.
I froze.
She got it?
I looked at the unopened handbag package sitting in front of me.
There were two.
One I mailed.
One empty retail box inside the larger package.
Then I understood.
Mark had opened some gifts before returning substitute packages.
The necklace.
The handbag.
The cookbook.
The originals were gone.
Sophie had included photographs.
Her wearing the necklace at eighteen.
Using the handbag at twenty-one.
Cooking from the book at twenty-five.
Mark had given them to her.
Then told her they came reluctantly.
Or from him.
Or only because he pressured me.
And he sent me fake returns so I would believe she rejected every gift.
My hands started shaking.
Sophie had documented everything.
Not because she planned revenge.
Because three months earlier, she discovered an old email account Mark had once used for family matters.
He had forgotten it still forwarded to an archived inbox tied to a tablet he gave her years ago.
Inside were messages.
His messages.
To her.
To me.
Drafts.
Forwarding rules.
Address changes.
He had inserted himself between us systematically.
The next item in the box was a small digital voice recorder.
There was a note attached.
PLAY FILE 4.
Mark moved toward me.
“Helen, don’t.”
I stepped back.
“Why?”
His face looked terrified.
“Because you don’t understand the context.”
That sentence was enough.
I pressed play.
Sophie’s voice came first.
She sounded nineteen.
“Dad, why does Helen keep sending gifts if she never wants to talk to me?”
Then Mark:
“Because she wants to look like the good person.”
My breath stopped.
Sophie:
“She doesn’t seem like that.”
Mark laughed softly.
“You didn’t live with her after you left.”
Then Sophie asked:
“Does she hate me?”
And my husband said:
“She thinks you made me choose.”
I sat down.
He had taken the exact fear he told me Sophie carried and fed the mirror version to her.
To me:
She thinks I chose you instead of her.
To Sophie:
Helen thinks you made me choose.
One lie.
Two victims.
One man in the middle deciding what each of us believed.
I looked at him.
“Why?”
He rubbed both hands over his face.
“It started after the wedding.”
“What started?”
“Sophie was angry.”
“At me?”
“No.”
The answer came too quickly.
I went still.
“At who?”
He looked away.
“At me.”
Finally.
The truth.
Sophie had not left because she hated me.
She left because she had discovered Mark had used money from a college account established by her late mother to cover wedding expenses and personal debt.
Not all of it.
Enough.
She confronted him.
He told her he would replace it.
She threatened to tell me.
Then he begged her not to ruin my marriage over “one mistake.”
When she still planned to tell me, he changed tactics.
He told her I already knew.
That I had agreed the money was “family money now.”
Sophie believed him.
Why wouldn’t she?
I had married him.
I had been excited about the wedding.
I had no idea her college account existed.
Sophie left for school believing I had helped her father take money her mother left her.
Then Mark told me Sophie resented the marriage.
He built the separation from both sides.
I felt physically sick.
“How much?”
He looked at me.
“How much money did you take?”
“Thirty-two thousand.”
I closed my eyes.
Our wedding had cost twenty-seven.
I had paid half from my savings.
He had told me his half came from an old business account.
There was no old business account.
There was Sophie’s mother’s money.
The box contained statements.
Transfers.
A repayment schedule Mark started two years later after Sophie threatened legal action.
He repaid the principal over time.
But he never told me.
Never told her the full truth either.
Instead, he made us distrust each other because if we ever spoke directly, his story would collapse.
I looked at the twelve returned gifts.
Twelve years.
Not one impulsive lie.
A system.
He had maintained it annually.
Birthday after birthday.
Phone call after phone call.
Every time I cried because another package came back, he comforted me.
Every time Sophie asked why I hated her, he comforted her too.
The cruelty of that almost made me lose my balance.
Then I found one final envelope inside the box.
Not addressed to me.
To Mark.
He grabbed it.
I held on.
“What is this?”
His face went white.
Sophie had written across the front:
DAD — IF YOU’RE THERE WHEN SHE OPENS THIS, READ PAGE ONE OUT LOUD.
I tore it open.
The first page contained only one sentence.
Tell Helen why you changed her phone number in my contacts twelve years ago.
I looked up.
Mark sat down.
And that was when I realized he had not merely redirected mail and lied about conversations.
He had made sure Sophie and I literally could not reach each other without going through him.
***
The phone-number trick was almost embarrassingly simple.
When Sophie left for college, Mark helped set up her new phone plan.
He saved my number incorrectly by one digit.
Then, months later, when I changed carriers, he told Sophie my new number had changed completely.
He gave her a prepaid number he controlled.
I never knew.
Whenever Sophie texted “me,” Mark saw it.
Sometimes he replied.
Sometimes he ignored her.
Sometimes he answered in a tone close enough to mine that a grieving nineteen-year-old believed it.
I wanted to deny that could work.
Then I read the messages.
He knew my phrases.
Of course he did.
Twenty years of marriage gives someone your vocabulary.
One message from “me” said:
Sophie, I think distance is best for everyone right now.
I had never written it.
Another:
Your father and I are trying to move forward. Please respect that.
Never mine.
I stared at Mark.
“You impersonated me.”
He whispered:
“Only a few times.”
That phrase almost made me laugh.
As if frequency changed identity theft inside a family.
Sophie had figured it out because one message arrived while Mark was physically sitting beside her at a graduation lunch years earlier.
At the time, she thought maybe he had scheduled it.
She ignored the inconsistency.
Then, recently, while clearing old devices, she found archived texts and discovered metadata showing the prepaid number was registered under Mark’s email.
That led her into the email archive.
Then the whole structure collapsed.
I called Sophie immediately.
Mark tried to stop me.
Not physically.
He said:
“Give her time.”
I looked at him.
“You’ve taken twelve years of time.”
Then I dialed.
She answered on the second ring.
Neither of us spoke.
Finally, she said:
“Helen?”
I started crying.
Not elegant tears.
The kind that close your throat.
“Yes.”
She inhaled sharply.
Then:
“I’m sorry.”
That was the first thing she said.
I almost broke.
“No. No, sweetheart.”
I had not called her sweetheart in twelve years.
Maybe ever.
“I am so sorry.”
She cried too.
Mark left the room.
For three hours, Sophie and I compared histories.
Not memories.
Histories.
She told me she tried calling after college finals.
I told her I never received the calls.
I told her I mailed gifts.
She told me she received several, but Mark framed them as reluctant gestures.
I told her I asked him repeatedly to invite her home.
She told me he said I refused.
Every piece fit.
Horribly.
At one point Sophie said:
“I thought you hated me because I reminded Dad of Mom.”
I covered my face.
“I thought you hated me because you thought I replaced her.”
We had each spent twelve years carrying the other’s imaginary rejection.
Mark manufactured it.
Why?
Control.
But not only control.
Shame.
He told himself at first that he was preventing one financial mistake from destroying our new marriage.
Then preventing Sophie’s anger from poisoning my relationship with her.
Then preventing me from learning he had lied.
Every lie required another barrier.
Eventually the barriers became the family structure.
That night, I slept in the guest room.
Mark slept somewhere else.
I did not ask where.
The next morning, I called an attorney.
Not because I had decided on divorce before breakfast.
Because I no longer trusted any financial story my husband had ever told me.
Her name was Priya Shah.
She specialized in family law and financial misconduct.
I brought the box.
She read enough to become very quiet.
“Was the college account legally Sophie’s?”
“I don’t know.”
“Was Mark trustee or custodian?”
“I don’t know.”
“Did you benefit from the money?”
“Apparently.”
“Did you know?”
“No.”
She nodded.
“Then we verify everything.”
That phrase grounded me.
Verify everything.
We did.
The account had been created under Sophie’s late mother’s estate plan.
Mark served as custodian while Sophie was a minor.
By the time he withdrew the money, Sophie was seventeen and months from majority.
The legal details were messy.
Some withdrawals might have had plausible educational or support labels.
The wedding transfers did not.
The principal had been repaid later.
That did not erase what happened.
Sophie had chosen not to pursue legal action years earlier because Mark convinced her exposure would destroy his marriage and “hurt Helen for no reason.”
I felt sick reading that.
He used me as leverage without my knowledge.
Again.
Priya advised me not to empty accounts or confront him about every transaction.
We ordered records.
Tax returns.
Bank statements.
Property documents.
I learned nothing else criminal.
I did learn something emotionally devastating.
Mark had maintained a separate emergency account for years.
Not hidden illegally.
Just undisclosed to me.
About seventy thousand dollars.
He called it “protection.”
Protection from what?
He never answered clearly.
Maybe divorce.
Maybe job loss.
Maybe consequences.
I looked at our marriage differently after that.
Not because spouses cannot have separate accounts.
They can.
Because Mark had built his entire adult life around controlling who knew what.
Information was his real currency.
Sophie came home two weeks later.
First time in twelve years.
I opened the door.
She stood there with one suitcase.
Thirty years old.
Not seventeen.
Not the girl I remembered.
She looked like her mother in ways I had almost forgotten.
Then she hugged me.
We both cried.
Mark was not home.
My choice.
Sophie walked through the house slowly.
Her old bedroom had become a study.
I apologized.
She laughed.
“I’ve lived somewhere else for twelve years.”
Fair.
Then she saw a photograph of her mother still on the bookshelf.
She touched the frame.
“You kept this?”
“Of course.”
She looked at me.
“Dad said you asked him to take her pictures down.”
I felt cold.
“No.”
He had moved several photographs after our wedding.
Told me Sophie requested it because seeing them with me in the house was upsetting.
Another lie.
Not financially useful.
Just controlling the story.
That was when I stopped asking whether the marriage could be repaired.
A person can make one terrible financial choice.
A person can panic.
A person can lie once and become trapped.
But Mark had curated reality for both of us.
That was not one mistake.
That was a way of living.
I filed for divorce the following week.
***
The divorce took fourteen months.
Longer than I wanted.
Cleaner than I feared.
Mark did not fight over the house because it was clearly separate property from before our marriage.
We divided marital assets.
Priya insisted on full disclosure.
The seventy-thousand-dollar account came into the calculation where appropriate.
I did not try to punish him financially beyond what the law and evidence supported.
That mattered to me.
I had spent twelve years inside a manufactured story.
I did not want revenge to become another one.
Sophie did not move in permanently.
Good.
We had both imagined reunion too dramatically at first.
After one week, we began stepping on each other.
She left wet towels on the bathroom floor.
I asked too many questions.
She hated breakfast before nine.
I remembered a seventeen-year-old who loved banana pancakes.
Thirty-year-old Sophie drank black coffee and skipped breakfast.
We were strangers with history.
That required humility.
So she rented an apartment nearby for three months.
We met twice a week.
Sometimes dinner.
Sometimes coffee.
Sometimes therapy.
Yes, therapy.
Her idea.
“I don’t want us to waste another decade assuming things.”
Fair.
The therapist asked us to tell the story from our own side without correcting each other.
That was hard.
I said:
“I believed you rejected me.”
Sophie said:
“I believed you resented me.”
Both true as experiences.
Both false as facts.
Then we talked about Mark.
The therapist warned us against turning our relationship into a permanent alliance against him.
At first, that offended me.
Then I understood.
If every conversation between Sophie and me revolved around what Mark did, he would remain the center.
We deserved a relationship with other subjects.
Books.
Work.
Food.
Bad television.
Her mother.
Yes, her mother.
That mattered most.
For years, I avoided talking about Emily because I feared Sophie would think I was pretending to replace her.
Sophie avoided talking about Emily because Mark told her it made me uncomfortable.
Once that lie disappeared, we talked openly.
Sophie told me her mother sang off-key.
I told her I knew because Mark once showed me an old video before our wedding.
Sophie laughed.
“She was terrible.”
I laughed too.
No competition.
No erasure.
One evening, Sophie brought over the cookbook I sent for her twenty-fifth birthday.
The real one.
Edges worn.
Pages stained.
“You used it.”
“Constantly.”
I cried.
She looked alarmed.
“Should I not have brought it?”
“No.”
I touched the cover.
“I thought you sent it back.”
She opened to the banana bread page.
There was a note in my handwriting inside.
For when you want the kitchen to smell like home.
I had forgotten writing that.
Sophie stared at it.
“I read this and thought you were being sarcastic.”
My heart hurt.
Mark had told her I resented that she never came home.
So even kindness arrived poisoned by context.
That realization taught us another lesson.
Words do not exist alone.
Who frames them matters.
During the divorce, Mark asked Sophie to meet.
She refused at first.
Then agreed months later.
Not because I encouraged her.
Because she wanted answers.
She told me afterward he apologized.
Not perfectly.
He still said things like:
“I was trying to keep the family together.”
Sophie answered:
“You kept two parts of the family apart.”
That sentence ended the meeting.
He wrote to me too.
A long letter.
I read it once.
He admitted taking the college money.
Admitted creating the prepaid number.
Admitted returning packages.
Admitted lying about photographs.
He said:
Every year I thought I would tell the truth after one more birthday, one more holiday, one more calm season.
I understood the mechanism.
Later is seductive.
Later is how one lie becomes twelve years.
Understanding did not create reconciliation.
Our divorce finalized.
Mark moved away.
He maintained limited contact with Sophie through letters for several years.
She chose the pace.
I stayed out of it.
That was important.
For too long, Mark had made himself the channel between us.
I refused to become the channel between them.
Meanwhile, Sophie and I built something unglamorous.
We missed calls.
Got annoyed.
Forgot birthdays once.
Yes, I forgot hers one year.
I panicked.
She laughed.
“You sent twelve gifts into a void. You’re allowed one bad calendar year.”
I laughed so hard I cried.
That birthday, I gave her nothing expensive.
We baked banana bread together.
It collapsed in the middle.
She took a photo.
“Mom would’ve made fun of this.”
I looked at her.
“Can I?”
“Absolutely.”
So I did.
And for the first time, the word mom in that kitchen did not threaten either of us.
There was another adjustment neither of us expected.
Sophie had built an identity around not needing me.
I had built one around not being wanted.
When those assumptions disappeared, we both felt strangely unsteady.
At therapy, Sophie admitted that even after learning the truth, part of her still braced for rejection whenever she called.
I admitted that every delayed reply made me fear she had changed her mind about having me in her life.
Our therapist asked us to stop treating ordinary delays like evidence.
So we made one ridiculous agreement.
If either of us was upset, we would say it.
No disappearing.
No coded silence.
No making the other person guess.
That sounded embarrassingly basic.
It was also harder than it looked.
The first time Sophie texted, “I’m annoyed, but I’m at work. Can we talk tomorrow?” I stared at the message and felt relieved.
Not because she was annoyed.
Because I did not have to invent the reason.
***
Three years after the divorce, Sophie asked me to help her move.
Not across the country.
Across town.
She had bought a small house.
Two bedrooms.
Yellow kitchen.
Tiny backyard.
The kind of place where every room had a purpose because there were not enough rooms to waste.
We carried boxes all morning.
Then the delivery truck arrived.
Same company logo as the truck that had brought the massive box to my house years earlier.
Sophie noticed too.
“Oh no.”
I laughed.
“What?”
“Trauma by logistics.”
We both laughed.
The driver brought in a dining table.
Nothing dramatic.
Still, for a moment, I saw the old cardboard box again.
The returned gifts.
The letters.
The recorder.
Evidence of twelve stolen years.
Sophie must have seen my face.
“You okay?”
“Yes.”
That answer was true.
The box no longer controlled the story.
It had opened it.
Different thing.
Sophie put the old packages in storage for a while.
Then eventually made a decision.
She kept the necklace.
The cookbook.
A scarf.
A framed card from one birthday.
The rest she donated or discarded.
I asked whether that felt strange.
“No.”
“Why?”
“Because the gifts were never the relationship.”
That was wiser than anything I had said.
She was right.
For years, I treated returned packages like proof of rejection.
Then after the truth, I almost treated them like sacred evidence of love.
Both gave objects too much power.
The relationship was in what we did now.
Coffee on Tuesdays.
Birthday calls.
Arguing over paint colors.
Sophie calling me when she had a terrible date.
Me calling her after a suspicious mammogram that turned out fine.
Real life.
Not twelve perfect years magically restored.
We could not recover those.
That grief remained.
Sometimes it arrived unexpectedly.
At her thirty-fifth birthday, Sophie said:
“You would’ve liked my college roommate.”
Simple sentence.
I smiled.
Then cried later in the car.
There were entire people in her life I should have known.
Graduations.
Jobs.
Breakups.
Illnesses.
Years.
Mark did not just steal contact.
He stole witness.
I had not witnessed Sophie becoming herself.
She had not witnessed me becoming older either.
That loss deserved grief.
Therapy taught us not to rush past it with gratitude.
We were lucky to have now.
We were also allowed to hate what was gone.
Both.
Five years after the box arrived, Sophie got engaged.
His name was Julian.
Kind.
Patient.
Terrible at baking.
He knew the whole family story before meeting me.
I appreciated that.
At dinner, he asked Sophie directly:
“Do you want me to tell Helen about the venue change?”
Sophie laughed.
“No intermediaries.”
He looked confused.
I said:
“Family rule.”
He nodded solemnly.
“Good rule.”
It became one.
No important messages through third parties unless necessary.
No “tell her I said.”
No “Dad says she thinks.”
Direct communication.
Simple.
Revolutionary.
At the wedding, Sophie carried a small photograph of her mother inside her bouquet.
She asked me to help pin it.
My hands shook.
“She should be here,” Sophie whispered.
“Yes.”
Then she looked at me.
“I’m glad you are too.”
That sentence healed something I had never asked her to heal.
I hugged her.
Not like a mother replacing someone.
Not like a stepmother auditioning.
Like Helen.
Her Helen.
That identity had taken fifteen years to exist honestly.
Mark was invited.
Sophie chose that.
He came.
Sat in the back.
We did not speak until the reception.
Then he approached.
“You look well.”
“So do you.”
Silence.
He looked toward Sophie dancing.
“I’m glad she has you.”
The sentence made me angry.
Not because it was false.
Because he had spent twelve years preventing exactly that.
Maybe he saw it in my face.
“I know,” he said.
I nodded.
That was enough.
No absolution at a wedding.
No scene.
Just acknowledgment.
Years later, when Sophie had a daughter, she asked whether I wanted to be called Grandma Helen.
I cried.
Of course I did.
Then immediately said:
“Only if that doesn’t feel strange.”
Sophie smiled.
“You still ask permission for everything.”
“Occupational hazard.”
Her daughter, Lucy, knew from childhood that Sophie had had two mothers in different ways.
Emily, who died.
And me, who arrived later.
No replacement language.
No secret.
No ranking.
When Lucy was six, she asked:
“Were you Mommy’s mom when she was little?”
I said:
“No. I met her when she was seventeen.”
Lucy frowned.
“That’s almost grown.”
“Exactly.”
“Then how did you become Grandma?”
I looked at Sophie.
She smiled.
I answered:
“Slowly.”
That was the truest word.
Slowly.
Not through marriage paperwork.
Not through gifts.
Not through persistence alone.
Through truth after lies.
Time after lost time.
Choice after choice.
Relationship after relationship.
Slowly.
When Lucy was born, I discovered another layer of grief.
I watched Sophie hold her daughter and suddenly understood all over again how young she had been when Mark separated us.
Seventeen.
Technically almost an adult.
Emotionally still someone who should not have been forced to decode competing stories from the parent she trusted most.
I told Sophie that once.
She shook her head.
“Don’t turn me into a victim forever.”
“I’m not.”
“You kind of are.”
She was right.
I had begun compensating for lost years by becoming overly careful with her.
Always asking permission.
Always apologizing.
Always watching for hurt.
Eventually Sophie said:
“Helen, I need you to be in my life, not tiptoe through it.”
That sentence changed how I showed up.
I stopped treating every disagreement like a possible rupture.
If she annoyed me, I said so.
If I annoyed her, she said so.
It turned out real closeness could survive friction.
That was something Mark’s system had never allowed us to learn.
***
Twelve years after the massive box arrived, Sophie brought it back.
The box itself.
Flattened.
Saved in her garage.
She carried it into my kitchen one afternoon and dropped it on the table.
“Why do you still have that?”
“I don’t know.”
We looked at the old shipping label.
My name.
Her return address.
The date that divided our lives into before and after.
Sophie said:
“I think I’m ready to throw it away.”
I laughed.
“Why are you telling me?”
“Because apparently this family needs direct communication.”
Fair.
We cut it apart for recycling.
That took less than five minutes.
Twelve years of lies had arrived in cardboard.
Five minutes turned the cardboard into strips.
There was something satisfying about the disproportion.
Before she left, Sophie pulled out one thing she had kept from the original contents.
A copy of the first email she ever sent me from college.
Helen,
I’m sorry I left without saying goodbye properly.
She handed it to me.
“I want you to have this.”
I read it again.
The sentence that mattered was farther down.
Please don’t think I hate you.
For twelve years, I had thought exactly that.
I folded the page.
“Thank you.”
Sophie leaned against the counter.
“Do you ever think about what would’ve happened if I hadn’t found the old tablet?”
“Yes.”
“Me too.”
Maybe Mark would have confessed eventually.
Maybe not.
Maybe I would have stopped sending gifts and gone to my grave believing Sophie rejected me.
Maybe Sophie would have believed I helped take her mother’s money.
That possibility still chills me.
Then Sophie said:
“I used to hate that everything depended on an accident.”
“What do you mean?”
“Finding the tablet. The archive. The old number.”
I nodded.
“But now?”
“Now I think the accident only exposed something that was already unstable.”
She was right.
Mark’s system required endless maintenance.
Every birthday.
Every phone number.
Every conversation.
Truth did not need that much work.
Once Sophie and I spoke directly, the structure collapsed within hours.
That became the biggest lesson of my life.
Manipulation thrives in distance.
Not geographical distance.
Relational distance.
When two people rely on a third person to explain what the other thinks, feels, wants, or said, power accumulates in the middle.
Healthy relationships shorten that distance.
Ask.
Call.
Verify.
Speak directly when possible.
I became almost annoying about that.
At work, if someone said:
“Janet said you were upset with me,”
I answered:
“Did Janet hear that from me?”
Usually no.
“Then ask me.”
Simple.
Sophie did the same.
Not suspicious.
Direct.
There is a difference.
Mark died years later.
Heart attack.
Unexpected.
Sophie called me.
We sat together at my kitchen table.
She cried.
Then apologized for crying.
I stopped her.
“He was your father.”
“He did terrible things.”
“Yes.”
“I loved him.”
“Yes.”
“That feels wrong.”
“No.”
Love is not a verdict.
That was another lesson.
Mark had loved Sophie.
I believe that.
He had also controlled her, lied to her, used her money, and isolated her from me.
Those facts do not cancel each other into simplicity.
Sophie attended the funeral.
I did too.
Not as wife.
Not as widow in any meaningful emotional sense.
As someone whose life had been intertwined with his for decades.
After the service, Sophie found a folder among his papers.
Inside were twelve returned-mail receipts.
Copies.
He had kept them.
Why?
We never knew.
Guilt?
Control?
Evidence?
Habit?
Sophie asked if I wanted them.
“No.”
Neither did she.
We shredded them.
No ceremony.
Some mysteries do not deserve preservation.
Years later, Lucy turned seventeen.
The age Sophie was when I entered her life.
At her birthday dinner, I watched Sophie look at her daughter with the exhausted tenderness parents carry when a child is almost grown.
After cake, Lucy disappeared upstairs.
Sophie laughed.
“She thinks we’re ancient.”
“She’s right.”
Then she looked at me.
“You were younger than I realized.”
“When I married your dad?”
“Yes.”
“So were you.”
We sat quietly.
Then Sophie said:
“I used to think if you had tried harder, maybe you could’ve figured it out.”
The sentence surprised me.
“Do you still?”
“No.”
She shook her head.
“You were working with the information you had.”
I felt tears.
She continued.
“And I was working with what I had.”
“Yes.”
“Dad was the only one who had the whole picture.”
“Yes.”
Then she smiled.
“Until the box.”
I laughed.
Until the box.
For twelve years, every birthday gift I sent my stepdaughter seemed to come back unopened.
By year thirteen, I finally stopped.
Three days later, she sent me every answer I had been missing.
At first, I thought the box revealed why she left.
It did.
But the deeper truth was not that Mark had fooled us.
It was how easily two people who cared about each other could be kept apart when each trusted the same person to interpret the other.
Sophie and I lost twelve years.
We never got them back.
What we got instead was something less cinematic and more valuable.
The chance to stop losing the next twelve.
And we did.
One phone call.
One coffee.
One birthday.
One direct conversation at a time.
The email Sophie gave me still sits in my desk.
Not framed.
Not displayed.
Just folded in a plain envelope.
Sometimes I forget it is there.
That is progress.
There was a time when I needed proof that she had not hated me.
Now I have years of ordinary evidence instead.
Missed calls.
Inside jokes.
Holiday arguments.
Photos of Lucy.
A spare key to Sophie’s house.
A recipe book with notes in both our handwriting.
The relationship no longer depends on proving the past was different from what we believed.
We already know.
What matters is that the present no longer requires translation through anyone else.