I Caught My Husband Plotting to Leave Me With Nothing at the Airport—He Never Realized My Phone Was Recording
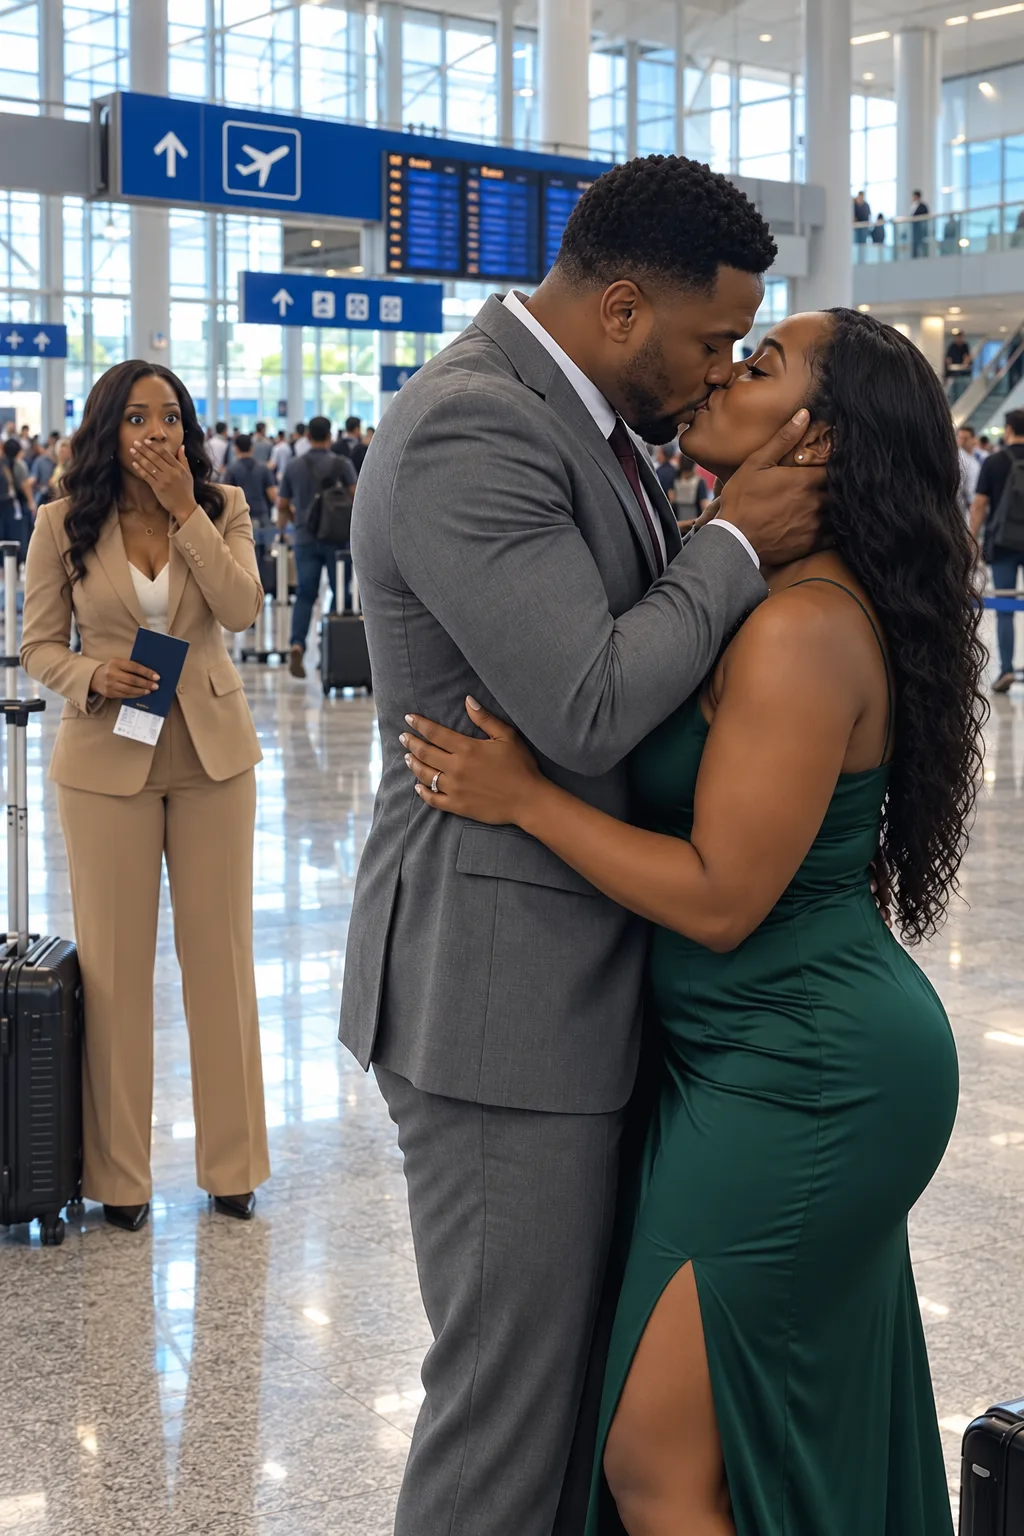
They passed within twenty feet of me.
Adrian never looked toward the pillar.
The woman did.
For one second, I thought she had seen me.
Then she glanced past me toward a departure board and kept walking.
I waited until they disappeared into the crowd, then stopped the recording.
Six minutes and twelve seconds.
I did not listen to it again there.
I called Jenna, who had already cleared security.
“I’m at the gate. Why?”
“I need the name of the divorce lawyer you used.”
Silence.
Then:
“Claire?”
“I saw Adrian with another woman.”
“Oh God.”
“That isn’t the worst part.”
I told her enough.
Not every sentence.
Just:
He talked about a transfer.
The accounts.
My house.
Jenna’s voice changed.
“Call Rebecca Chen.”
I did.
Rebecca answered from her office.
She asked three questions before anything else.
“Are you physically safe?”
“Yes.”
“Does Adrian have access to firearms?”
“No.”
“Do you believe money is moving today?”
“I think so.”
“Come here. Do not confront him. Do not log into accounts from a device he controls if you think he monitors it. Bring your identification and whatever financial records you can access lawfully.”
Facts.
Instructions.
I needed both.
On the drive, I kept thinking about the papers I had signed two weeks earlier.
Adrian had launched a logistics software company called Northbridge Systems eighteen months ago.
At first, it was exciting.
He had spent years in corporate operations.
He hated bureaucracy.
He wanted something of his own.
I supported him.
Too much, maybe.
I refinanced my house and contributed $180,000 toward Northbridge’s launch.
The documents I remembered signing described it as a loan to the company secured by Adrian’s membership interest.
Two weeks ago, he brought home another stack.
“Routine cleanup before the next funding round.”
I skimmed.
He pointed.
I signed.
One document had been notarized at our bank the next morning.
That memory made my stomach turn.
Rebecca did not tell me I had lost my house.
She told me not to guess.
We pulled the county property record.
The deed still showed:
Claire Bennett, sole owner.
No new deed recorded.
No new lien beyond the refinance I already knew about.
Relief hit me hard.
Rebecca said, “Good. Now stop assuming ‘handled’ means completed.”
Next, the bank.
Our joint checking account had $74,000 that morning.
A pending outgoing wire for $68,500 appeared.
Destination:
Northbridge Holdings LLC.
I recognized the name vaguely.
Another entity.
“Can we stop it?”
Rebecca said:
“You can call the bank as an account owner and report that you dispute the pending transfer. Do not misrepresent anything. Tell them exactly what you know.”
I called.
Because the wire had not settled and one joint owner disputed it, the bank froze it pending review.
Adrian had initiated the transfer using our joint account credentials.
The brokerage also showed a request to liquidate nearly $210,000 in mutual funds. I disputed that request before any money left, and outgoing distributions were restricted pending review.
I had not “won” anything.
I had simply stopped two pending transactions long enough to understand them.
Rebecca had me print transaction history.
Then we looked at the business documents.
I had copies in email.
The “routine cleanup” packet contained ordinary corporate consents, a personal guaranty for a new $500,000 credit line, and one document I had not understood at all: an assignment of my existing $180,000 loan claim against Northbridge Systems to Northbridge Holdings LLC, an entity Adrian controlled.
If valid, I had signed away a six-figure repayment right.
“Can he do that?”
Rebecca read carefully.
“You signed it.”
“I didn’t know what it was.”
“That matters, but it does not automatically erase the signature. We need to understand how the document was presented, whether material facts were misrepresented, and whether there was consideration.”
“Consideration?”
“What did you receive in exchange?”
I stared.
“Nothing.”
The assignment stated:
For value received.
No amount.
No separate payment.
No schedule.
Rebecca’s eyebrows lifted.
“That helps.”
Then she found the notarized page.
Not the assignment.
A separate limited power of attorney.
My blood went cold.
It authorized Adrian, for thirty days, to sign documents “necessary to refinance or restructure obligations associated with Northbridge Systems and related entities.”
At the bank, he had told me it merely let him finish business closing papers if timing slipped.
The authority was broad, but not unlimited. It did not authorize him to deed away my house or control my personal accounts.
Rebecca said:
“We revoke this now.”
She drafted a written revocation.
We sent it to Adrian by tracked email through counsel.
Sent it to the lender named in the packet.
Sent it to Northbridge’s registered agent.
Sent it to the bank where the business line was being processed.
No confrontation.
Just documents and time stamps.
Then Rebecca looked at my phone.
“The recording.”
I handed it over.
She did not play it immediately.
“Where were you?”
“Public terminal. Behind a pillar.”
“Were you part of their conversation?”
“No.”
“Then do not post this. Do not send it around. Recording laws and privacy expectations can be complicated, and admissibility is separate from usefulness. Preserve the original file and metadata. We can treat it as a lead while we verify the underlying transactions independently.”
That was not the answer I wanted.
I wanted the recording to be decisive.
Instead, Rebecca told me to preserve it and verify everything independently.
Better.
By the time I left Rebecca’s office, I knew Adrian was having an affair, had tried to move our liquid joint money, and had maneuvered me into signing away a major financial claim.
I still did not know what “the house is handled” meant.
That answer came at 4:17 p.m.
A title company called me.
“Mrs. Bennett, we received notice that you revoked Mr. Whitmore’s power of attorney. We have suspended tomorrow’s closing.”
I stopped walking.
“What closing?”
There was a pause.
“The refinance involving your residence.”
My knees nearly gave out.
“What refinance?”
A $420,000 cash-out loan.
Secured by my house.
Application signed partly by Adrian under the limited power of attorney.
Closing scheduled for the next morning.
Proceeds designated to pay off my existing smaller refinance and send roughly $185,000 net cash to Northbridge Holdings.
Adrian had told the title company the power of attorney covered the transaction.
Rebecca’s revocation arrived hours before closing.
The house was not gone, but he had tried to make it collateral for his plan.
I finally understood the airport conversation.
Once the transfer clears.
No accounts.
No access.
The house already handled.
He was not planning to leave me poor by magic.
He was trying to create facts faster than I could react.
And he had almost succeeded.
***
I did not go home that night.
Rebecca advised me that emotional separation and legal possession were different issues.
The house was mine before marriage.
That did not mean I should change locks while Adrian still lived there without first understanding local occupancy rules and safety considerations.
So I stayed with Jenna.
Adrian called at 6:12.
I did not answer.
Then:
Where are you?
Then:
Why did you freeze the accounts?
Then:
What the hell did you tell the title company?
There it was.
No:
Are you okay?
No:
What happened?
He already knew exactly which transactions had failed.
I forwarded the messages to Rebecca.
She responded:
Do not engage tonight unless necessary for safety or logistics.
At 8:30, Adrian emailed me.
Claire,
I don’t know what you think is happening, but you have now jeopardized a financing transaction that Northbridge depends on. The house refinance was part of the restructuring documents you signed. The account transfers were temporary capitalization. We need to talk before you create irreversible damage.
I read it twice.
Then laughed.
Before I create irreversible damage.
Rebecca filed for divorce the next morning after I authorized her.
Not because infidelity guaranteed a legal advantage.
Because I no longer trusted Adrian with finances and did not want another week of pretending.
She also sought temporary financial orders preventing unusual transfers, new liens, or disposal of major marital assets without consent or court approval.
The court granted interim restraints after notice and hearing procedures appropriate to the case.
No secret ex parte seizure of his life.
No freezing every dollar he owned.
Both of us could pay ordinary expenses.
Business operations could continue subject to defined limits.
Major transfers required disclosure.
The recording never appeared in the initial filing.
We did not need it.
Bank records.
Brokerage requests.
The loan file.
The title-company documents.
The signed assignment.
Those existed independently.
Adrian hired counsel.
Good.
His first formal response painted a very different story.
Northbridge was struggling with cash flow after a large customer delayed payment.
Adrian claimed I knew the business needed financing.
True.
He claimed I had repeatedly said I would “do whatever it takes” to keep the company alive.
Probably true in ordinary conversation.
He claimed the limited power of attorney allowed the refinance.
Disputed.
He claimed the assignment of my $180,000 company loan had been part of a broader marital financial plan.
False from my perspective.
But the signature was mine.
That would require evidence.
Then came the woman from the airport.
Her name was Caroline Ross.
She was not merely “a client.”
She was a private credit consultant helping Northbridge structure emergency financing.
She was also sleeping with my husband.
Both facts were true.
Rebecca told me not to collapse them into one.
“Was she part of the fraud?”
“I heard her laughing about me losing everything.”
“That is relevant. But we need to know what she actually did.”
Subpoenaed records later showed Caroline had advised on the credit line and refinance structure.
She received financial documents Adrian supplied.
Some listed me as consenting.
She never met me.
She had asked, in one email:
Has spouse signed off on collateral package?
Adrian replied:
Yes. POA covers closing.
That helped Caroline.
Then another message hurt her:
Once this is done, I file and keep the operating company clean.
She replied:
Just make sure she can’t claw the cash back before we close.
That was ugly.
Potentially important.
Still not proof she forged anything.
She had not created my signature.
She had not notarized the POA.
She had not initiated the joint-bank transfer.
She advised Adrian about timing and asset movement while knowing divorce was imminent.
Her own lawyer later argued she believed the transactions were authorized and lawful.
Possible.
Morally rotten.
Legally fact-dependent.
Then we discovered the most damaging document.
The title company had required an owner-occupancy and consent affidavit because the house was titled only in my name.
Adrian had signed my name under the power of attorney.
The affidavit stated I understood the refinance proceeds would be directed to Northbridge Holdings.
Did the power of attorney permit him to sign that?
That became a central question.
The POA covered documents “necessary to refinance or restructure obligations associated with Northbridge Systems and related entities.”
The house loan was not an obligation of Northbridge before closing.
It was new debt secured by my separate property.
Rebecca’s position:
The POA did not authorize creating a new lien on my separately titled residence.
Adrian’s counsel:
The refinance was expressly part of restructuring business obligations, and I had executed the POA after reviewing the financing plan.
Except I had not reviewed that plan.
The notary became important.
She worked at our bank.
She testified later that she confirmed my identity and witnessed me sign the POA.
She did not explain legal consequences.
Not her job.
She remembered me asking:
“This is only for business closing papers, right?”
Adrian answered:
“Yes, only Northbridge.”
The notary could not recall whether I saw the house refinance term sheet.
She did remember no such term sheet was on her desk.
That mattered.
So did email history.
The night before I signed, Adrian sent me:
Need your signature tomorrow so I can finalize investor docs if timing slips.
No mention of home refinancing.
No mention of assigning my loan claim away.
No mention of draining joint accounts.
Misrepresentation was becoming easier to show.
Then forensic accounting entered.
Not because every divorce requires it.
Because Adrian’s entities had multiple transfers and related-party accounts.
A neutral financial expert traced money.
Northbridge Systems.
Northbridge Holdings.
A consulting LLC owned by Caroline.
Two business credit cards.
Our joint accounts.
My original $180,000 contribution.
The accountant found that Northbridge Systems had not simply hit a short-term cash crunch.
It had been insolvent on a balance-sheet basis for months.
Adrian knew.
He had been paying older vendors using new customer deposits.
Not necessarily criminal by itself.
Dangerous.
He also transferred $96,000 from Systems to Holdings during the marriage.
About $42,000 then went to Caroline’s consulting company.
Some payments matched documented work.
About $17,500 had no clear invoice support.
The rest paid business expenses.
No suitcase of stolen cash.
A distressed company with poor boundaries.
Rebecca looked at the report.
“This is why we trace instead of narrate.”
I was learning to hate how often she was right.
***
The airport recording became relevant months later.
By then, both sides knew it existed.
Rebecca disclosed it through discovery after consulting local counsel about its use.
We did not claim it was automatically admissible.
We preserved the original file.
Produced it under protective terms.
Let the lawyers argue.
More important, the recording gave us phrases to test against documents.
“Once the transfer clears.”
Which transfer?
The pending $68,500 wire.
Or the refinance proceeds?
Discovery showed Adrian had planned both.
“No accounts.”
What did that mean?
An email to Caroline answered:
After joint cash is capitalized, Claire can fight over reimbursement later. She won’t have liquidity to fund a long case.
That sentence made me physically ill.
He was not trying to make me legally own nothing.
He was trying to make access difficult.
Litigation leverage.
Different.
Still ugly.
“The house is handled.”
That referred to the next-day refinance.
Again, documentary confirmation.
The recording mattered less as evidence of exact legal wrongdoing than as a map.
Adrian’s strategy was not brilliant.
It was aggressive timing.
Move joint cash into an entity he controlled.
Use the POA to close a house-backed refinance.
Convert my loan claim against Northbridge into an assignment to his holding company.
Then file divorce before I understood.
He assumed transactions completed before filing would be harder and more expensive to unwind.
He was probably right about the expense.
Wrong about invisibility.
Every transfer generated records.
The affair itself mattered little to property law compared with the financial conduct.
Our jurisdiction did not award me a moral bonus because he kissed Caroline at an airport.
Affair spending could matter if marital funds were dissipated.
So the accountant traced that too.
Hotels.
Meals.
A weekend trip.
Gifts.
About $14,300 over eight months.
Not hundreds of thousands.
We negotiated a settlement credit for agreed marital spending on the affair.
Caroline was not sued simply for being the affair partner.
I wanted to at first.
Rebecca said:
“For what legal claim?”
That ended it.
Later, there was a separate civil claim related to the financing.
Not against Caroline initially.
Against Adrian and Northbridge Holdings.
We sought rescission of the assignment transferring my $180,000 loan claim.
The refinance had never closed, so there was no house lien to unwind.
The bank transfer never settled.
The brokerage liquidation request was canceled before money left.
Those were near misses, not completed thefts.
The assignment was different.
Signed.
Effective on paper.
Adrian refused to reverse it voluntarily.
So we litigated.
I testified about what he told me.
He testified I understood.
The notary testified.
Emails were admitted.
Draft versions of the packet showed something important.
Three days before I signed, the assignment had a separate cover page titled:
TRANSFER OF SPOUSAL LOAN INTEREST.
In the version Adrian emailed me, that cover page was removed.
The document remained buried behind corporate consents.
He said formatting changed for efficiency.
The judge did not find that explanation persuasive.
The court rescinded the assignment based on misrepresentation and lack of informed assent under the facts presented.
Not because wives are automatically protected from signing bad documents.
Because evidence showed Adrian materially misrepresented what I was signing.
My $180,000 claim returned to me.
Then another problem:
Northbridge could not pay it.
A legal claim is not the same as cash.
The company entered a formal restructuring process with creditors.
My loan joined the queue according to its legal priority.
I recovered only part.
About $112,000 over time.
Painful.
Realistic.
Adrian did not have $68,000 sitting in a suitcase to make me whole.
The business had lost money.
Some value was simply gone.
The divorce settlement dealt with remaining assets separately.
House:
Mine as premarital separate property, subject to reimbursement arguments concerning marital contributions to principal and improvements.
We settled those claims.
Adrian received no ownership interest in the house itself.
He did receive a credit for a documented portion of marital funds used toward mortgage principal during marriage.
I hated that emotionally.
Rebecca said:
“Property classification is not a punishment system.”
Again.
Retirement:
Divided according to marital portions.
Joint cash:
What remained split after accounting for temporary expenses and credits.
Business interest:
Adrian kept Northbridge equity, which by then was worth little.
My separate loan claim remained mine after rescission.
Affair spending:
Settlement credit to me.
Legal fees:
Each paid most of their own, though the court shifted a portion to Adrian because some of his nondisclosure and document conduct increased litigation cost.
Not all.
No bankruptcy of the villain.
No mansion award.
Just accounting.
The criminal side was narrower.
A prosecutor reviewed the attempted refinance and financial documents after the lender referred suspicious activity.
No charge for “trying to take the house.”
That phrase was legally sloppy.
The investigation focused on whether Adrian made materially false statements to the lender and whether signatures/authorizations were used fraudulently.
He eventually entered a plea to a reduced offense involving false statements in a credit application.
Probation.
Fine.
Business-compliance conditions.
No prison.
The prosecutor did not charge Caroline.
Evidence showed she knew divorce was coming and advised on timing.
It did not prove she knew the POA had been obtained through misrepresentation.
Morally, I had opinions.
Legally, those opinions were not evidence.
Caroline lost her consulting relationship with the lender after an internal review.
That was an employment/business consequence.
Not something I engineered.
By then, I barely cared.
The strangest moment came at mediation.
Adrian sat across from me.
Not beside Caroline.
Alone with his lawyer.
He looked exhausted.
He said:
“I never meant for you to be homeless.”
I stared.
“You tried to put a new mortgage on my house without telling me.”
“I thought the business would survive.”
“That is not the same answer.”
He rubbed his face.
“I thought if I got the financing closed, I could stabilize everything before filing.”
“And the accounts?”
“I wanted liquidity on my side.”
“Exactly.”
He looked at me.
“I was afraid you would freeze me out.”
I laughed once.
“So you tried to do it first.”
He said nothing.
That silence was the most honest answer he ever gave me.
***
The divorce became final fourteen months after the airport.
Longer than I wanted.
Shorter than it could have been.
The day the judge signed the final decree, I did not celebrate.
I went home.
Sat on the floor in the living room.
The house looked exactly the same.
That mattered.
My father’s restored banister.
The uneven patch in the hallway where he had taught me to sand drywall.
The kitchen window he insisted on replacing himself because contractors “never square old frames properly.”
Adrian had said:
The house is handled.
It was not.
Not because I had outsmarted him completely.
Because the refinance was stopped before closing and the title never changed.
Timing mattered.
Records mattered.
Independent advice mattered.
I began therapy.
Not because I could not function.
Because I could function too well.
Within weeks of the airport, I became efficient.
Passwords changed.
Credit frozen.
Beneficiaries reviewed.
Bank alerts activated.
Mail redirected.
Documents scanned.
I could organize betrayal like a project.
Then at night, I shook.
My therapist asked:
“What part are you grieving?”
“The marriage.”
“Only?”
“No.”
I was grieving the version of myself who signed papers because my husband pointed at a line.
That shame was harder.
She challenged it.
“Was trust irrational before you had evidence of betrayal?”
“No.”
“Then why are you rewriting trust as stupidity?”
I did not have an answer.
I learned something important.
Being deceived does not mean you failed every earlier moment.
Adrian exploited legitimate trust.
That was his choice.
My responsibility was what I did after evidence appeared.
Still, I changed.
Future financial rule:
No signing complex documents without independent review when my own property or personal guarantees were involved.
Not because every spouse is dangerous.
Because material transactions deserve comprehension.
Simple.
I also learned the difference between privacy and evidence collection.
The airport recording became the thing friends fixated on.
“You got him on tape!”
Not exactly.
I had captured a conversation in a public airport area.
Its legal use was complicated.
The case was won and settled primarily through ordinary records.
I stopped letting people tell the story as though one secret recording destroyed Adrian.
His documents did.
His transfers.
His emails.
His loan applications.
His own timing.
The recording simply made me look.
That distinction became important when my brother joked that I should “record every man from now on.”
No.
Hypervigilance is not healing.
I dated no one for almost two years.
Not as a vow.
I was tired.
Jenna moved closer after her conference job turned remote.
We had dinner every Thursday.
She still apologized for not noticing Adrian.
I finally told her:
“You were my friend, not my private investigator.”
That helped both of us.
Northbridge dissolved eighteen months after the divorce.
Its remaining software assets were sold to a competitor.
Creditors received partial distributions.
I received the final payment on my reinstated loan claim.
Total recovery:
$112,430.
Loss:
$67,570 plus opportunity cost.
I kept the loss on a spreadsheet for years.
Then deleted the spreadsheet.
Not because the money stopped mattering.
Because I no longer needed to calculate betrayal monthly.
Adrian worked again.
A salaried operations role.
No founder title.
No access to large financing decisions at first due to his probation conditions.
I learned this through required financial disclosures during final enforcement, not gossip.
Part of me wanted him permanently ruined.
Another part knew that was neither realistic nor necessary.
Accountability does not require lifelong economic death.
He paid ordered amounts.
Completed probation.
Moved on.
So did Caroline.
I saw her once.
Not planned.
A hotel lobby at a professional event three years later.
She froze.
I froze.
She said:
“Claire.”
I said:
“Caroline.”
She looked as if she wanted to apologize.
I did not want it.
I said:
“I’m not discussing Adrian.”
She nodded.
Then:
“For what it’s worth, I was wrong.”
I could have asked:
About the affair?
The financing?
Laughing at me?
Instead:
“Okay.”
I walked away.
Closure rarely arrives with enough chairs.
Sometimes it is thirty seconds beside an elevator.
At work, I became more vocal about financial literacy programs.
Not because my marriage made me an expert.
It didn’t.
I invited an estate attorney and CPA to speak at our women’s professional group about property titles, guaranties, powers of attorney, and joint accounts.
No personal story.
Just tools.
The most attended session was:
WHAT ARE YOU ACTUALLY SIGNING?
I sat in the back and smiled.
My father would have loved that title.
One other consequence stayed with me after the decree.
For almost a year, every unfamiliar envelope made my stomach drop.
I worried Adrian had opened another account, pledged another asset, or put my information somewhere I had not found.
The forensic review had uncovered no secret mortgage, no second deed, and no additional personal guaranty beyond the disputed financing package.
Still, my nervous system did not care about audit conclusions.
So I froze my credit, set transaction alerts, reviewed all three credit reports, and changed every recovery email and security question I could remember.
Rebecca told me:
“Do this because it is sensible, not because we have evidence another fraud exists.”
That distinction mattered.
Risk management can become obsession if fear is allowed to set the scope.
After twelve months with no new problems, I reduced the checks.
Quarterly instead of weekly.
Then only when normal financial life required them.
Nothing dramatic happened.
That was the goal.
Recovery was not catching one final hidden scheme.
It was learning that an ordinary month with no new surprise was allowed to count as good news.
***
Five years after the airport, I was forty-three.
The house was still mine.
I had refinanced once more.
This time, deliberately.
Lower rate.
No business proceeds.
No husband pointing at signature lines.
I read everything.
Asked questions.
The loan officer probably hated me.
Fine.
Jenna framed one of my father’s old carpentry sketches and gave it to me for my birthday.
It hangs in the hallway.
Not the airport recording.
Not the divorce decree.
Not the rescinded assignment.
The house existed before Adrian.
It deserved to exist after him without becoming a monument to betrayal.
I eventually dated again.
Marcus Reed.
A civil engineer.
Widowed.
Two adult daughters.
The first time he mentioned combining travel expenses through a shared account, my entire body tensed.
He noticed.
“We don’t have to.”
“I know.”
“Do you want separate?”
“Yes.”
“Okay.”
That simple answer mattered.
We maintained separate primary accounts.
Opened one small joint account for trips after a year.
No drama.
No proof of commitment required.
Trust grew through repeated ordinary consent.
Marcus knew the airport story.
Not every legal detail.
Enough.
He once asked:
“Do you regret recording them?”
I thought.
“No.”
“Would you do it again?”
“That exact situation? Probably.”
“Do you record me?”
“No.”
“Good. I sing in the car.”
I laughed.
That was how life returned.
Adrian contacted me once after all obligations ended.
Email.
No demand.
Claire,
I have thought a lot about the phrase you said at mediation: “You tried to do it first.”
You were right.
I believed divorce was going to become a contest over who controlled liquidity, so I acted before there was even a divorce.
I told myself I was protecting the company.
I was protecting leverage.
I am sorry.
He also wrote:
I used your trust as evidence of permission instead of something I had to keep earning.
That line stayed with me.
I did not answer.
Not because the apology was worthless.
Because no reply was needed.
My relationship with money changed too.
Before Adrian, I thought ownership documents were boring background.
Afterward, I briefly thought they were armor.
Eventually, I learned they are neither.
They are information.
A deed says who holds title.
A POA says what authority exists.
A guaranty says who promises payment.
A bank agreement says who can move funds.
Those papers cannot make a relationship honest.
But ignoring them does not make love more pure.
I taught my nieces that.
Not:
Never trust your spouse.
Instead:
Understand what you sign.
Know where your accounts are.
Know whose name is on the house.
Maintain enough independent access that one person cannot make you financially helpless overnight.
That is not planning for divorce.
It is adult competence.
The airport recording still exists.
Encrypted archive.
My attorney told me what to retain and what I could discard after the relevant matters concluded.
I kept the original only because it formed part of the case history and associated legal records.
I do not listen to it.
I do not need Adrian saying:
That idiot is about to lose everything
living in my head on demand.
The phrase lost power once I understood how wrong it was.
He had assumed completed transactions would become irreversible facts.
They didn’t.
Some were stopped.
Some were rescinded.
Some losses remained.
That last part matters.
I did not escape untouched.
I lost nearly $68,000 on the business loan.
Paid substantial legal fees even after the partial fee shift.
Spent fourteen months divorcing someone I had once trusted.
Lost the imagined future.
Those are losses.
A good ending does not require pretending they vanished.
What I did not lose:
The house.
My retirement.
Most joint savings.
My right to challenge documents.
My ability to work.
My friends.
My judgment.
That last one took longest to believe.
For months, I replayed the moment he said:
You trust me, don’t you?
I heard accusation in it.
As though my yes had caused everything.
Now I hear something else.
He knew trust mattered.
That was why he invoked it.
Manipulation works by attaching the desired action to a valued identity.
Trusting wife.
Supportive partner.
Team player.
Good person.
The answer is not to become none of those things.
It is to separate identity from consent.
I can love you and read the document.
I can trust you and ask what the transfer does.
I can support your business and refuse to mortgage my house.
I can be married and keep my own account.
Those sentences would have sounded cold to me at thirty-eight.
At forty-three, they sound like adulthood.
Marcus and I married?
Not yet.
Maybe someday.
He once joked:
“If I propose, should I bring a ring or a term sheet?”
“Both.”
He laughed.
I did too.
Healthy love survived the joke because neither of us was using paperwork to hide.
Five years after the airport, I returned there with Jenna.
Different trip.
Different gate.
We passed the charging stations.
I recognized the pillar immediately.
For one second, my stomach tightened.
Then Jenna said:
“Coffee?”
“Yes.”
We kept walking.
No dramatic pause.
No reenactment.
That was healing.
The airport became an airport again.
People ask what I would have done if I had confronted Adrian beside that pillar.
Maybe he would have lied.
Maybe he would have canceled the wire.
Maybe he would have rushed the refinance.
Maybe everything would have unfolded differently.
I do not know.
What I know is that silence for those few hours gave me time to replace panic with information.
That was useful.
Not because revenge is best served cold.
I hate that phrase.
Because financial danger is easier to address before announcing you know about it.
Secure records.
Get advice.
Understand what is pending.
Then act lawfully.
That is what saved the house.
Not my smile.
Not the recording.
Not some secret genius plan.
Timing and professionals.
The thing Adrian never understood was that marriage had not made me powerless.
He had only made me uninformed.
Those are not the same condition.
Information changed mine.
At the airport, he said I was about to lose everything.
Five years later, I know what “everything” actually means.
It was never the brokerage account.
Never the house.
Never even the marriage.
Everything would have been losing the ability to decide what happened next.
He almost took that by moving faster than the truth.
Almost.
May you like

Then I heard him.
And from that moment forward, the decisions became mine again.