My Parents Gave All Three Family Houses to My Brother — "Daughters Marry Out." I Signed Without Arguing. Then on Thanksgiving, I Told Them What I'd Done Before I Left
Chapter One — Six Years of Keeping the Books
I want to describe, before recounting everything that unfolded around those three property deeds, exactly what six years of managing my family's finances actually involved, because understanding the genuine scope of that work matters enormously to understanding how devastating it felt to watch my parents hand ownership of everything I'd helped protect and build directly to my brother, based on nothing more than the specific circumstance of his gender.
I'd started informally managing my parents' household finances during my mid-twenties, initially just helping my mother organize bills and tax documents during a particularly overwhelming period, work that gradually expanded, over the following years, into comprehensively managing the family's entire financial picture — the mortgages on all three properties, my father's construction business accounts, tax planning, and the careful, ongoing work of preventing the kind of financial chaos my brother Malcolm's repeated poor decisions consistently threatened to create.
I want to be honest about exactly how much unpaid, largely unacknowledged labor this work actually represented. I managed these finances alongside my own demanding career building an independent financial consultancy, understanding my family responsibilities as simply an extension of genuine love and commitment rather than anything I expected specific credit or compensation for at the time.
Chapter Two — The $180,000 Loan
I want to explain, in careful detail, exactly what happened two years before that devastating dining table confrontation, when my father's construction company faced genuine, immediate collapse following a series of failed projects and mounting debt obligations that threatened not just his business, but the family home itself, given how thoroughly he'd leveraged the property against the company's operating credit.
I provided a private loan of $180,000 from my own savings and a home equity line I secured against my own condo, structured, at my own insistence, through a properly drafted, notarized legal agreement rather than any informal family arrangement. I understood, even then, that protecting my own financial interests required genuine legal documentation rather than simply trusting my parents' verbal assurances, a specific, careful instinct that would eventually prove considerably more consequential than I could have anticipated at the time.
The agreement, drafted by an attorney I retained specifically for this purpose, secured my loan against all three family properties — the duplex, the lake house, and the downtown townhouse — meaning that any subsequent transfer of those properties would remain subject to my security interest until the full loan balance was repaid.
Chapter Three — Watching the Pattern Develop
I want to describe, honestly, the specific pattern of favoritism I'd witnessed throughout my entire life, understanding that the devastating dining table confrontation represented less a sudden, isolated betrayal and more the culmination of decades of accumulated evidence about exactly how my parents valued their two children differently.
Malcolm had received, over the years, considerable financial support for various business ventures that consistently failed — a restaurant investment that collapsed within eighteen months, a real estate flip that lost considerable money, a series of increasingly desperate "opportunities" that my parents funded repeatedly despite his consistent inability to demonstrate genuine financial discipline or business acumen. I, by contrast, had built a genuinely successful independent consultancy through years of careful, disciplined work, receiving, in exchange, considerably less enthusiastic acknowledgment and, at family gatherings, persistent questions about when I planned to "settle down" rather than any genuine celebration of my professional achievements.
Chapter Four — What Happened at That Dining Table
I've already described the specific, devastating sequence of that confrontation — my mother's casual delivery of "daughters marry out," my father's dismissive instruction not to "make this emotional," Malcolm's smug confidence that I'd simply move to Canada and forget the entire situation. I won't retell that full sequence again, but I want to describe what was happening in my mind during those specific, quiet moments before I signed those transfer documents.
I understood, staring at those three deeds, that immediate, emotional resistance would accomplish nothing beyond confirming my family's apparent belief that I was simply being "emotional" about a decision they'd already fully made. I also understood, with the same careful, disciplined financial thinking that had guided my management of their finances for six years, that my $180,000 security interest remained fully intact regardless of who technically held title to those properties — a fact my parents, in their focus on the symbolic gesture of transferring ownership to Malcolm, had apparently never fully considered.
Chapter Five — What Diane Explained
I've already described my meeting with Diane Okafor before my flight to Vancouver, her confirmation that my security interest would remain attached to the properties regardless of the title transfer. I want to describe, in more detail, exactly what that legal protection actually meant in practical terms, and why I felt such calm, confident certainty that Malcolm would eventually default on the underlying obligations.
"Your security interest gives you the legal right to force a sale or foreclosure on any of the three properties if the underlying loan obligations aren't met according to the original agreement's terms," Diane explained. "Given that your brother now holds title, any additional debt he takes on against these properties would need to account for your existing security interest, assuming proper title searches are conducted. If he attempts to leverage the properties further without addressing your interest first, he'd be creating a legally precarious situation that could unravel quite dramatically if he can't service all the resulting obligations."
I understood, absorbing this explanation, that I held considerably more genuine power over those three properties' fate than my parents' confident, dismissive transfer had accounted for — a fact I intended to let unfold naturally, understanding Malcolm's well-documented pattern of financial recklessness, rather than taking any immediate action myself.
Chapter Six — Building a New Life
I want to describe, briefly, the genuine, considerable satisfaction of building an independent life in Vancouver over those following months, understanding that this new chapter represented not simply an escape from my family's dysfunction, but a genuine opportunity to build something entirely my own, unencumbered by the specific patterns of undervaluation I'd navigated for most of my adult life.
My position in financial compliance provided both genuine professional challenge and, notably, a considerably healthier work environment than the constant, uncompensated emotional and financial labor I'd provided my family for years. I built a small but genuine circle of friends, began exploring a city I found genuinely beautiful and welcoming, and, for the first time in longer than I could remember, experienced the specific relief of a life not constantly organized around managing other people's financial chaos.
Chapter Seven — Malcolm's Lifestyle
I want to describe, based on what I observed through social media and occasional updates from extended family members who remained in contact with me, exactly how Malcolm chose to manage the considerable financial windfall those three properties represented once he'd received clear title to all of them.
He leased a Porsche within the first month, financed additional renovations to the lake house that considerably exceeded any reasonable budget, and, according to what I'd eventually confirm through the formal financial investigation that followed his default, developed an increasingly serious gambling habit that consumed considerable resources through online sports betting platforms. He treated the properties, exactly as I'd predicted to Diane, as simply liquid wealth to be leveraged and spent rather than genuine, appreciating assets requiring careful management.
Chapter Eight — What Malcolm Actually Did
The forensic financial review conducted once the formal default proceedings began revealed that Malcolm had taken out two additional loans against the lake house and downtown townhouse within four months of receiving title, using the properties as collateral for both a considerable personal loan and a business line of credit connected to yet another failed venture — a cryptocurrency trading platform that collapsed within weeks of his investment, taking a substantial portion of the borrowed funds with it.
These additional loans, critically, hadn't accounted for my existing security interest, either because Malcolm genuinely didn't understand its legal significance or because he'd simply assumed, given our parents' dismissive attitude toward my financial contributions, that it represented no genuine obstacle to his plans. Either way, this oversight created exactly the kind of legally precarious, overleveraged situation Diane had described as the likely outcome of Malcolm's well-documented financial recklessness.
Chapter Nine — The Thanksgiving Call
I've already described the specific confrontation of that Thanksgiving phone call — my mother's casual demand that I wire Malcolm $30,000, my calm response suggesting she ask him what had actually happened to those three houses. I want to describe, now, exactly what happened once I finally explained, in full, exactly what I'd done before leaving.
"Mom," I said, once the silence following my initial response had stretched long enough to make clear she genuinely didn't understand what I meant, "two years before you gave those houses to Malcolm, I loaned Dad $180,000 to save his construction company. That loan was legally secured against all three properties. When you transferred title to Malcolm, my security interest stayed attached. If he's defaulted on new loans he's taken out against those houses, using them as collateral without accounting for what he still legally owes me, that's not something I can simply wire away with a favor. That's a legal mess he created himself, the same way he's created every other financial mess in his life."
The silence that followed, exactly as the original account described, carried a specific, devastating weight — my mother finally, completely understanding the full scope of what her dismissive "daughters marry out" declaration had actually cost the family she'd been so certain she was protecting by favoring Malcolm.
Chapter Ten — What Happened Next
The following months brought exactly the kind of financial unraveling Diane had originally predicted, once Malcolm's additional loans began defaulting and creditors, discovering my existing, properly documented security interest during their own title searches, began pursuing formal legal action to resolve the resulting conflict between competing claims on the properties.
I want to describe, honestly, the specific, complicated satisfaction of watching this situation unfold — not out of any particular desire to see my family suffer, but out of a genuine, hard-earned recognition that the specific financial protection I'd built for myself years earlier, dismissed at the time as unnecessary "temporary paperwork," had ultimately proven considerably more consequential than my parents' confident belief that transferring title alone would fully settle the question of who actually controlled those properties.
Chapter Eleven — The Legal Resolution
The formal legal proceedings, once fully underway, ultimately resulted in a foreclosure sale of the lake house and downtown townhouse, the proceeds first satisfying my original $180,000 security interest before addressing the additional debt Malcolm had accumulated, with whatever remained divided according to the complex web of competing claims his financial recklessness had created.
I retained the original red-brick duplex, the one property Malcolm hadn't managed to leverage before the broader situation collapsed, understanding that my grandfather's original construction of that specific home carried a particular sentimental significance I wanted to preserve regardless of everything else that had unfolded.
Chapter Twelve — What Happened to My Family
My relationship with my parents remains, even now, considerably strained following everything that unfolded. My mother's specific reaction to fully understanding the consequences of her own dismissive treatment of my financial contributions has moved, gradually, from initial anger directed at me for "not warning them" toward something closer to genuine, if painful, reckoning with exactly how thoroughly her favoritism toward Malcolm had ultimately cost the family considerably more than it would have cost to simply treat both her children with equal genuine respect and consideration from the beginning.
Malcolm's own financial recovery from this collapse has required considerable time, his credit and financial standing severely damaged by the default and subsequent foreclosure proceedings. I haven't spoken with him directly since that Thanksgiving call, understanding that whatever relationship we eventually rebuild, if any, will require considerably more genuine accountability from him than he's shown any indication of developing so far.
Epilogue — What the Insurance Actually Protected
I think often about that specific, deliberate phrase I used with Diane, two years before that devastating dining table confrontation — calling my carefully documented loan agreement "insurance" rather than simply a family loan, understanding, even then, some instinct that my parents' verbal assurances alone might not prove sufficient protection for the considerable resources I was contributing to our family's stability.
My parents assumed, sliding those three deeds across the table with such casual, dismissive confidence, that transferring title alone would fully settle the question of who actually controlled our family's most significant assets. They never once accounted for the possibility that the daughter they'd so confidently written out of the family legacy had already, years earlier, secured exactly the kind of legal protection that would ultimately determine those properties' fate considerably more decisively than any dining table declaration about who "carries the family name" ever could.
I don't know if my parents will ever fully understand or acknowledge exactly how much their favoritism ultimately cost them. What I know, building my own genuinely secure, independent life in Vancouver, is that the specific, careful discipline I brought to protecting my own interests years before anyone in my family believed I'd need to protect them ultimately proved considerably more valuable than whatever recognition or inheritance I might have received had I simply, quietly accepted my parents' explicit declaration that I mattered less than my brother.
My Husband Sent Me to Paris So His Family Could Take My House and Savings—But I Secretly Came Home and Recorded Everything
PART 2
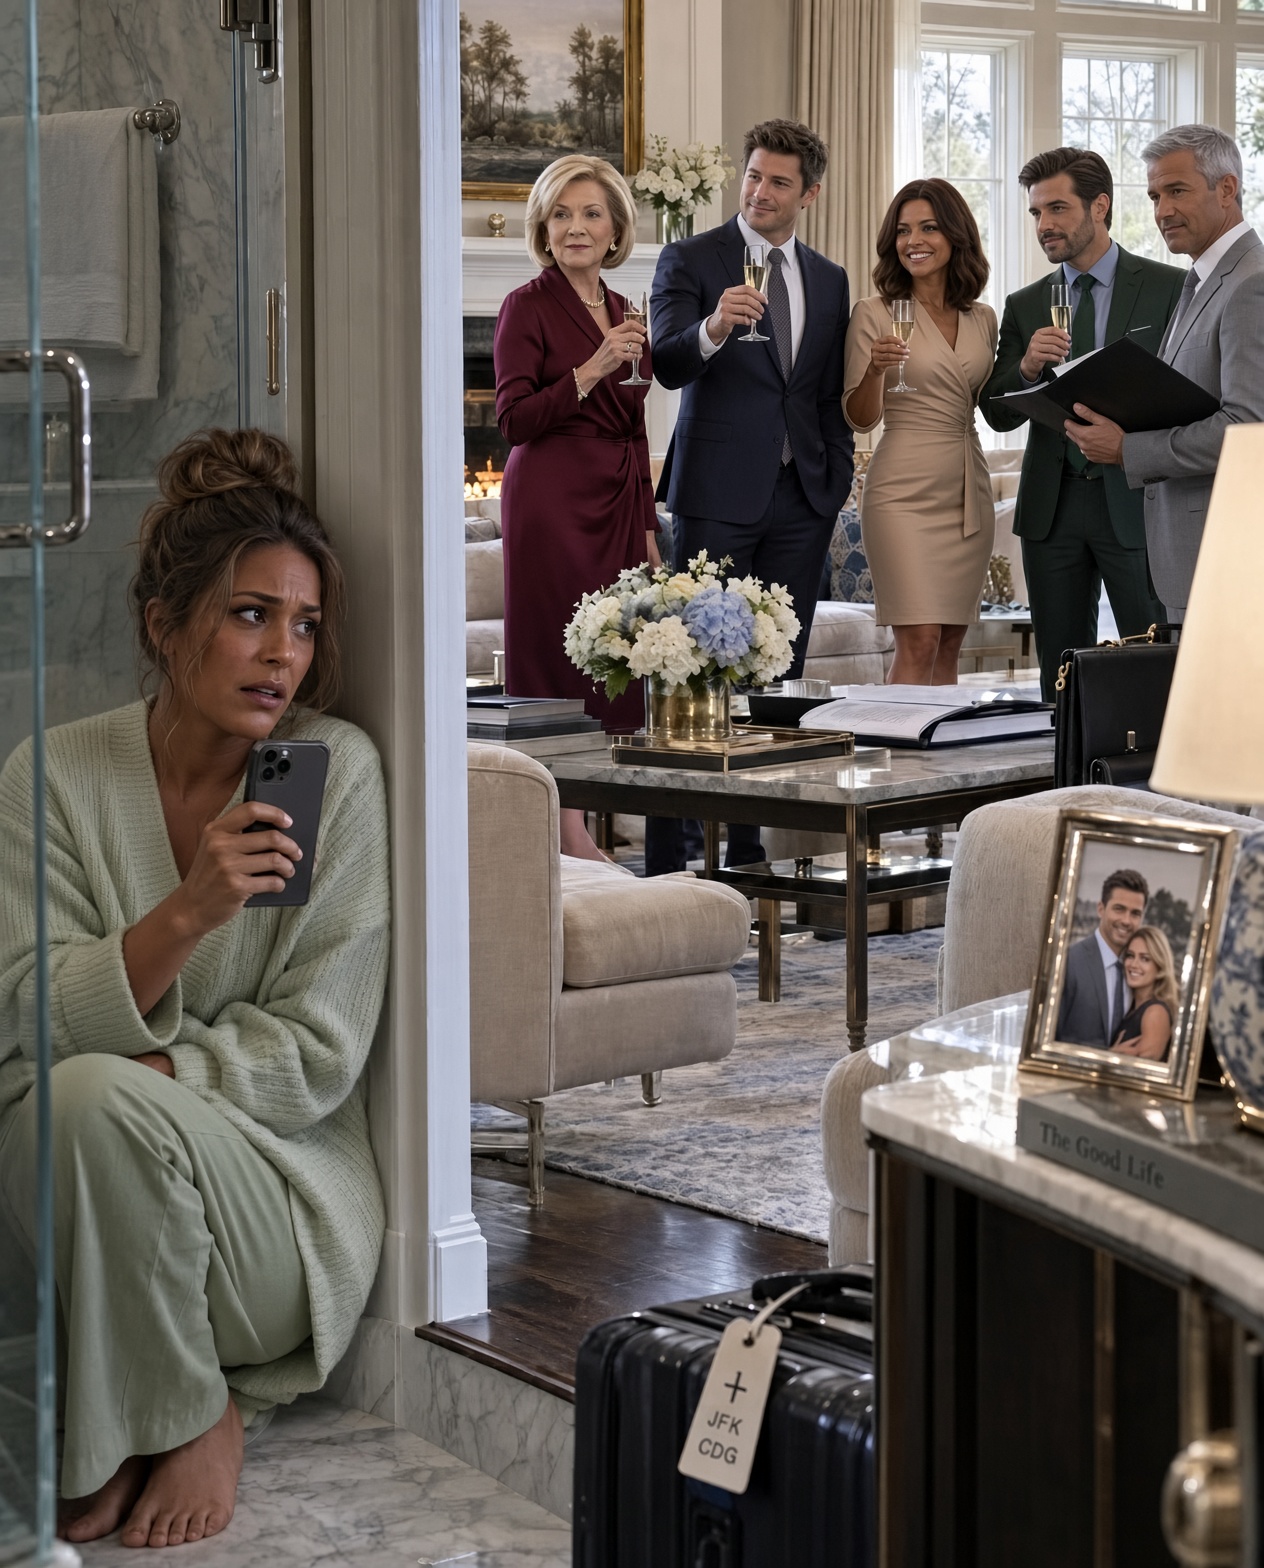
For several seconds, nobody downstairs spoke.
Then the man with the briefcase answered.
“We do nothing unless she notices.”
My pulse hammered.
Four hundred eighty thousand dollars.
Richard said, “She audits companies for a living. Eventually she’ll
notice.”
Eric laughed softly.
“She hasn’t noticed yet.”
That sentence hurt because he believed my trust was stupidity.
The stranger explained that the money had been moved in smaller
transfers through accounts I already used for taxes, insurance, and
investments, then redirected through an entity called Meridian Advisory
Partners.
I knew the name only vaguely from a quarterly statement.
Then Sarah asked, “Does Vanessa know about the Paris part?”
Vanessa.
A name I had never heard.
Eric answered immediately.
“She knows enough.”
Eleanor laughed.
“She’s waited long enough for you.”
My fingers went numb.
Richard asked, “When is she moving in?”
“Not immediately,” Eric said. “That would look bad.”
I pressed the phone closer to the vent.
My husband was not merely planning to use my money.
He had another woman waiting for my place in his life.
PART 3
The conversation continued.
Eric planned to file for divorce while I was overseas. Richard needed
the proposed $1.25 million credit line to keep his failing cybersecurity
company, Nebula Systems, alive until investors supposedly arrived.
The stranger warned them that my Greenwich house was titled solely to me
and had a clear premarital ownership history.
Eric replied, “That’s what the home-equity documents are for.”
“If underwriting verifies directly with Clara, this stops.”
“They won’t. She’ll be in France.”
Paris was not a gift.
It was an operational window.
I stayed hidden for another forty minutes while they discussed my tax
returns, brokerage statements, divorce timing, and Vanessa Hale.
From fragments, I learned Eric had been seeing her for at least eighteen
months.
When the group finally moved away from the staircase, I texted Evelyn.
Are you home?
Her answer came instantly.
Yes.
Can I come through your backyard?
I’ll unlock the gate.
I waited until music started downstairs, slipped out through the back
staircase, and crossed into Evelyn’s yard with only my purse and phone.
My suitcase remained in the mudroom.
For a few more hours, I wanted them to believe I was going to Paris.
PART 4
Evelyn opened her kitchen door before I reached it.
“What happened?”
I put my phone on her table.
“Enough.”
My first call was to Rachel Monroe, the attorney who had handled my
grandmother’s estate and later reviewed my prenuptial agreement.
I played part of the recording.
She stopped me after seven minutes.
“Where are you?”
“Across the street.”
“Are you safe?”
“Yes.”
“Do not confront them. We protect you first.”
Rachel warned me not to empty joint accounts or retaliate financially.
Instead, we preserved evidence and contacted institutions about
suspected unauthorized activity.
My bank added restrictions against remote changes pending verification.
My brokerage added enhanced authentication to individually owned
accounts and began reviewing transfers.
Rachel connected me with forensic accountant Marcus Lee.
I also alerted my employer’s information-security team because Eric had
access to our home network.
At 12:17, Eric texted:
Boarding soon? ❤️
Rachel suggested I preserve the status quo until we knew more.
I replied:
About to turn my phone off. Thank you again for the surprise.
He answered:
You deserve it. Love you.
I took a screenshot.
PART 5
By afternoon, the gray SUV was gone.
Eric left later.
I returned briefly, with Rachel on speaker.
Five champagne glasses sat on the dining table.
The printer’s recent-job history showed eleven documents printed that
morning.
I photographed the queue without tampering with anything.
Then I packed documents and property that were mine, along with
medication and my grandmother’s jewelry.
I left Eric’s belongings untouched.
That evening, Marcus called.
“I found Meridian.”
The transfers totaled $479,800.
“Where did the money go?”
“I’m tracing it.”
An hour later he called again.
“At least $312,000 reached Nebula Systems.”
“And the rest?”
“Still tracing.”
“Who owns Meridian?”
A pause.
“Vanessa Hale.”
The affair and the financial scheme were connected.
The next morning, Rachel began seeking appropriate emergency civil
protections and record preservation.
We notified the lender considering Nebula’s $1.25 million facility that
I disputed any guarantee or collateral authorization bearing my name.
Underwriting stopped.
Then Eric called.
PART 6
I ignored the first call.
His text arrived seconds later.
Thought you were in Paris. Call when you land.
Then:
Clara?
Rachel said I no longer needed to maintain the fiction.
I sent one sentence.
I did not board the plane.
The phone rang instantly.
I answered with Rachel listening.
“Where are you?” Eric demanded.
“Safe.”
“What happened?”
“I came back to the house.”
Silence.
Then the question that told me everything.
“How much did you hear?”
Not why did you come back.
Not are you okay.
How much did you hear.
“Enough.”
“Clara, I can explain.”
“Do not explain anything to me by phone.”
“Did Evelyn put you up to this?”
“This is between you and me.”
“No, it isn’t. You’re about to destroy Richard’s company over a
misunderstanding.”
“Did I authorize a $1.25 million guarantee?”
Silence.
“Did I authorize transfers to Meridian?”
“Those were investments.”
“Did I authorize them?”
He hung up.
Rachel said quietly, “Do not call him back.”
I didn’t.
PART 7
Eric filed for divorce the next morning.
Filing first did not give him ownership of the truth.
Rachel explained that Connecticut property division could involve
complex equitable considerations, so we would rely on evidence rather
than slogans about who “automatically” owned what.
The house’s title history, my grandmother’s ownership, the prenuptial
agreement, source of funds, and the attempted encumbrance all mattered.
The lender produced the disputed guarantee.
My signature looked convincing at a glance.
It did not survive scrutiny.
The document also contained a notary acknowledgment from someone I had
never met.
The man with the briefcase was identified as Martin Keene, a private
financing consultant hired by Richard.
He retained counsel quickly.
Through his attorney, Martin claimed Eric had represented that I
verbally approved the financing and would sign later.
He admitted receiving samples of my signature.
He denied creating the disputed signature himself.
Nobody on my side guessed.
We preserved records.
The institutions investigated.
Facts first.
PART 8
Marcus traced another $167,000 from Meridian into expenses connected
with a commercial condominium whose beneficial owner was Vanessa.
I sat in the hotel room staring at the transaction map.
Some of my money appeared to have supported Richard’s company.
Some appeared connected to the woman sleeping with my husband.
For the first time since the bathroom, I cried.
Then Vanessa emailed me.
Five words.
I didn’t know you existed.
I forwarded it to Rachel.
Two days later, Vanessa’s attorney contacted ours.
Her version was complicated.
Eric had told her we were separated.
He claimed we remained legally married because of unresolved property
negotiations.
He told her the Greenwich house was jointly owned and that I lived
mostly in Manhattan.
She admitted Meridian received money Eric described as marital
investment funds.
She claimed she did not know the true source.
I did not know which parts were accurate.
But she produced eighteen months of messages.
In them, Eric repeatedly called me his “ex.”
PART 9
The messages about Paris were worse.
Three weeks before giving me the tickets, Eric wrote:
She’ll be gone long enough to finish the paperwork.
Vanessa replied:
Are you sure she agreed?
Eric:
She doesn’t need to know every detail yet.
That sentence suggested Vanessa had questions.
It did not automatically erase her responsibility for allowing money
through Meridian.
But I refused to make her my primary enemy simply because she was the
other woman.
My vows had been with Eric.
My financial trust had been placed in Eric.
His choices belonged to him.
Sarah called next.
“I didn’t know about Vanessa,” she cried.
“I don’t care. What did you know?”
She admitted knowing Richard needed money and that Eric said I would
refuse.
She knew documents were being prepared.
When I asked whether she knew my signature was copied, she went silent.
“I thought Eric had authority,” she finally whispered.
“Why?”
“He’s your husband.”
“Marriage is not permission to sign my name.”
“I know that now.”
“You should have known it then.”
PART 10
Nebula Systems was in worse condition than anyone admitted.
It had lost two major clients and was weeks from missing payroll.
Richard believed private equity investors were about to rescue it.
They were not.
The investors had serious concerns about revenue concentration and
internal controls.
The proposed credit line would not have solved the underlying problem.
It would have delayed it.
My unauthorized money had already been delaying it for nearly two years.
Marcus mapped the transfers.
Whenever Nebula approached a cash crisis, money moved from my accounts
through Meridian.
Richard paid vendors or payroll.
What may have begun in Eric’s mind as temporary borrowing became
entitlement.
Entitlement became a system.
Then Eleanor sent me a letter accusing me of abandoning forty-three
employees by refusing the guarantee.
The argument was emotionally effective.
It was also backwards.
If a company could survive only through unauthorized transfers and a
disputed guarantee, the employees were already at risk.
My refusal did not create that risk.
Management did.
PART 11
Nebula entered restructuring three weeks later.
Some employees were laid off.
Others stayed.
Assets were sold, and a healthier competitor acquired one product
division.
It was painful.
But no questionable guarantee was used to postpone reality.
Meanwhile, I remained out of the Greenwich house until temporary
arrangements were handled through counsel.
I did not lock Eric out.
I did not throw his possessions onto the lawn.
Eventually, he moved to an apartment and I returned.
The first night alone, I walked through the dining room where they had
raised their glasses.
Then I climbed upstairs.
I entered the bathroom.
The marble floor was still cold.
I sat exactly where I had hidden.
This time I was not afraid someone would open the door.
The house felt different.
Not because ownership had changed.
Because I had.
PART 12
Back home, ordinary objects began revealing a second life.
Restaurant receipts on nights Eric said he worked late.
A hotel loyalty statement sent to an old email address.
A second phone charger in his desk.
Nothing dramatic alone.
Together, they formed a pattern.
I stopped searching after an hour.
More betrayal was not going to create more understanding.
I already knew enough.
The financial investigation continued for months.
Real disputes did not resolve with one dramatic courtroom speech.
They resolved through account records, authorization logs, dates,
credentials, testimony, forensic analysis, and negotiation.
The $1.25 million facility never funded.
That was the largest immediate protection.
Of the roughly $480,000 previously moved, a substantial portion was
eventually traced and addressed through recoveries, settlements, and the
divorce process.
I did not recover every dollar.
But I recovered enough truth to stop questioning my own memory.
PART 13
Six weeks after filing for divorce, Eric asked through counsel whether I
would consider marriage counseling.
His letter blamed pressure from his family.
He called the affair a product of loneliness.
He called Paris a desperate mistake.
I laughed at that phrase.
Paris required airline tickets.
Hotel reservations.
Timing.
Family coordination.
Documents.
A financing consultant.
A false narrative about my absence.
A mistake happens in a moment.
This was a project.
I declined counseling.
Later, I agreed to one meeting in Rachel’s conference room.
Eric looked thinner.
“Ten years,” he said.
“Yes.”
“You can really throw away ten years?”
“I’m not throwing them away. I’m ending what exists now.”
“I never meant to hurt you.”
“You planned to file while I was overseas.”
“I thought Richard would repay everything.”
“You moved money for two years.”
He had no answer.
Then I asked about Vanessa.
“I loved her,” he whispered.
Past tense.
I felt almost nothing.
That was when I knew the marriage was over.
PART 14
“Did you love me?” I asked.
“Yes.”
The answer came immediately.
I believed him.
People sometimes imagine betrayal proves love never existed.
I no longer think life is that simple.
Eric may have loved me.
He also lied, exploited my trust, had an affair, and participated in a
plan to use my assets without valid permission.
Love did not cancel conduct.
“I believe you,” I said.
Hope appeared in his face.
Then I continued.
“And it isn’t enough.”
His expression collapsed.
For ten years, I had believed love was the strongest fact in marriage.
Trust was stronger.
Respect was stronger.
Safety inside another person’s knowledge of you was stronger.
Eric knew my accounts, habits, travel preferences, family history, and
attachment to my grandmother’s house.
He had turned knowledge created by intimacy into operational
intelligence.
I could not rebuild from that.
PART 15
Vanessa eventually agreed to meet with attorneys aware.
She looked nothing like the villain I had imagined.
She looked exhausted.
“I’m sorry,” she said.
“For what?”
“For not asking more questions.”
She admitted she knew Eric remained legally married.
She had accepted his explanation because it was convenient.
She allowed Meridian to receive funds without insisting on understanding
their source.
“I should have known better.”
“Yes.”
She nodded.
She cooperated with tracing and recovery.
I did not forgive her that day.
I also did not hate her.
Responsibility did not require me to simplify everyone into heroes and
villains.
Evelyn became the closest thing the story had to a hero.
She hated that description.
“I looked out a window.”
“You stopped me from getting into a car.”
“You would have figured it out.”
“When?”
She shrugged.
“Probably before they got the house.”
“That is not comforting.”
I took her to dinner anyway.
We raised glasses.
“To suspicious neighbors,” I said.
“To women who keep spare keys,” she replied.
PART 16
The divorce took fourteen months.
The settlement was confidential.
The house remained mine under the final resolution.
Eric retained his own separate property and whatever the negotiated
agreement provided regarding marital assets.
I did not leave him penniless.
I did not want to.
Justice was not annihilation.
Richard lost control of Nebula during restructuring.
Sarah and Richard separated for several months and later attempted
counseling.
Eleanor stopped contacting me after Rachel requested that communication
go through counsel.
Martin’s professional consequences were handled by the institutions and
authorities reviewing his conduct.
There was no single moment when everyone who hurt me collapsed.
Life simply reorganized around consequences.
My hardest consequence was internal.
I stopped trusting my own instincts.
How had a senior risk auditor missed this?
My therapist, Dr. Naomi Ellis, challenged me.
“Was your marriage supposed to be an audit engagement?”
“No.”
“Were you supposed to verify every statement your husband made?”
“No.”
“Then why are you judging yourself for trusting someone whose role
required trust?”
I had no answer.
PART 17
I reviewed the warning signs anyway.
Not to blame myself.
To understand.
Eric had become more interested in my account structures.
He asked whether the Greenwich house could support business borrowing.
He encouraged me to consolidate statements.
He offered to handle more household administration because I worked long
hours.
Each behavior had an innocent explanation.
Together, in hindsight, they formed a pattern.
But hindsight is dishonest when it pretends the ending was obvious from
the beginning.
It wasn’t.
I trusted my husband because he was my husband.
The wrongdoing belonged to the person who abused that trust.
I changed my financial systems.
Separate credentials.
Independent alerts.
Annual reviews of authorization settings.
No shared passwords for individually owned accounts.
Clear records.
Not because I expected another partner to steal from me.
Because good controls protect everyone from confusion, error, coercion,
and temptation.
PART 18
I also stopped apologizing for protecting my grandmother’s house.
Eleanor had always made sole ownership sound selfish.
It wasn’t.
My grandmother left it to me.
Preserving it did not make me less committed to marriage.
A spouse can be loved without being granted ownership of everything that
existed before them.
Two years after the divorce, I finally went to Paris.
Alone.
Not because I needed a cinematic recovery.
Because Eric had turned the city into a tool and I wanted it to become a
place again.
I stayed near Luxembourg Gardens, but not at the hotel he booked.
The first morning, I bought coffee and walked without an itinerary.
Nobody knew where I was.
Nobody needed my signature.
Nobody was waiting for me to leave the country so they could move money.
I sat beside the fountain and cried.
Then a child nearly crashed a toy sailboat into my shoe, and I laughed.
Paris became Paris again.
Not evidence.
PART 19
On my third day, Evelyn called.
“How terrible is it?”
“Awful. Bread everywhere.”
“I knew it.”
“I may never recover.”
“Bring me wine.”
I did.
I also bought myself a small blue box.
The original Paris tickets had arrived in one.
For months, that color reminded me of Eric’s note:
Let me take care of you for once.
Inside my new box, I placed a simple silver key pendant.
Not because jewelry heals betrayal.
Because I liked the symbolism.
A key.
My house.
My accounts.
My choices.
Mine to share.
Not anyone else’s to assume.
When I returned, a letter from Sarah was waiting.
She apologized specifically for entering my house, participating in the
financing discussion, and focusing on saving Nebula after hearing about
the $480,000.
She wrote:
I wanted Richard’s company to survive so badly that I stopped caring
what survival cost someone else.
That was honest.
I replied:
Thank you for saying it clearly.
Nothing more.
PART 20
Eric contacted me only once after the divorce.
He emailed on what would have been our twelfth anniversary.
He wrote that he had spent years blaming pressure, Richard, Eleanor,
Vanessa, and fear of losing status.
Then:
None of them logged into your accounts for me. None of them stood in our
kitchen and planned to send you away. I did those things.
I appreciated the accountability.
I did not answer.
Not every apology requires a conversation.
My career changed too.
The experience made me more attentive to insider risk.
At a conference, I gave a presentation about trusted-access abuse in
corporate systems.
I never mentioned my marriage.
A junior auditor asked, “How do you create controls without destroying
trust?”
I answered:
“Good controls do not replace trust. They keep trust from being asked to
do a job it was never designed to do.”
I wrote that sentence down later.
It applied to more than companies.
PART 21
Evelyn eventually sold the house across the street and moved closer to
her daughter.
Before leaving, she handed me a spare key.
“To what?”
“My new house.”
“You haven’t even moved yet.”
“I know you. You’ll visit every six months and bring expensive wine.”
“Fair.”
Then she looked at me.
“You’re different.”
“Older?”
“Less apologetic.”
That was true.
I had spent years making my competence smaller so Eric would never feel
overshadowed.
I softened facts to preserve comfort.
I stopped doing that.
Three years after the Paris trip that never happened, I hosted
Thanksgiving.
Friends filled the house.
Someone raised a glass.
For one second, my body remembered champagne downstairs and cold marble.
Then Evelyn said, “To Clara, who finally learned to buy decent wine.”
Everyone laughed.
So did I.
The sound of glasses touching became only a sound again.
The house became home.
PART 22
I eventually renovated the bathroom.
The plumbing genuinely needed work.
The contractor offered marble almost identical to the old floor.
I chose warmer stone.
When the renovation was finished, I lay on the new floor once.
Ridiculous, perhaps.
Necessary, definitely.
I looked at the ceiling and thought:
This is where I heard the truth.
Not where my life ended.
The $480,000 also became smaller in my mind over time.
At first, the number consumed me.
Later, it became one line in a larger story.
Some money returned.
Some did not.
I would never call the loss worthwhile.
Pain does not become a bargain simply because we survive it.
But I stopped allowing missing money to occupy more emotional space than
the life I still possessed.
My career.
My home.
My friends.
My judgment.
My future.
And eventually, my ability to trust again.
PART 23
Five years after the divorce, I met Daniel Mercer, a landscape
architect.
On our fourth date, he asked why I had unusually elaborate account
alerts.
I told him the short version.
He did not say, “I would never do that.”
He said, “That makes sense.”
Months later, when the relationship became serious, we discussed money
directly.
What was separate.
What might become shared.
What access meant.
What neither person needed access to.
It was the least romantic conversation imaginable.
It made me feel safer than roses.
I did not marry quickly.
I did not refuse marriage either.
I simply stopped treating trust as blindness.
Sometimes I think about the version of me who nearly climbed into that
Uber.
Suitcase in the trunk.
Paris ticket in my purse.
Eric standing in the doorway pretending he wanted me to rest.
If Evelyn had not noticed the SUV, I might have gone.
I do not know exactly what would have happened.
That uncertainty no longer terrifies me.
PART 24
My survival did not depend on being omniscient.
It depended on responding when the truth appeared.
I listened.
I recorded.
I called professionals.
I preserved evidence.
I resisted the urge to destroy everything in anger.
I let facts do what facts do.
Eric thought sending me to Paris would create four quiet days in which
he could rearrange my life.
Instead, twenty minutes after saying goodbye, I came home through the
garden mudroom.
I hid in my own bathroom.
I heard my husband raise a glass with his family.
I heard them discuss my home.
My savings.
My signature.
My reputation.
Then I heard the amount they had already taken.
Four hundred eighty thousand dollars.
And finally, I heard Vanessa’s name.
For a while, I thought that name was the moment everything changed.
It wasn’t.
The real change happened when my hands were shaking on the marble floor
and, instead of rushing downstairs to demand explanations from people
already committed to deceiving me, I opened the recorder.
PART 25
I stopped asking betrayal to explain itself.
I started preserving the truth.
Years later, the house is still mine.
But that is not the victory I value most.
The money mattered.
The legal outcome mattered.
The evidence mattered.
What mattered more was learning that love does not require surrendering
control of your identity, property, or judgment.
Trust should be given.
Access should be understood.
And when someone uses intimacy as a way around your boundaries,
protecting yourself is not betrayal.
It is clarity.
Eric sent me to Paris because he believed absence would make me
powerless.
Instead, his plan gave me the first quiet moment in ten years when I
finally heard exactly who he had become.
Once I heard it, I never pretended not to know again.
The last time I stood in the renovated bathroom, morning light crossed
the new stone floor.
Daniel called from downstairs asking whether I wanted coffee.
“Yes,” I called back.
Then I smiled at the ordinary sound of someone asking instead of
deciding for me.
I walked downstairs.
My phone stayed in my pocket.
I no longer needed to record the people I loved.
That, more than the house or the recovered money, was how I knew I had
finally come home.