My Son Tried to Move Me Out of My Own House—The Next Morning, His Bank Froze His Business Credit Line
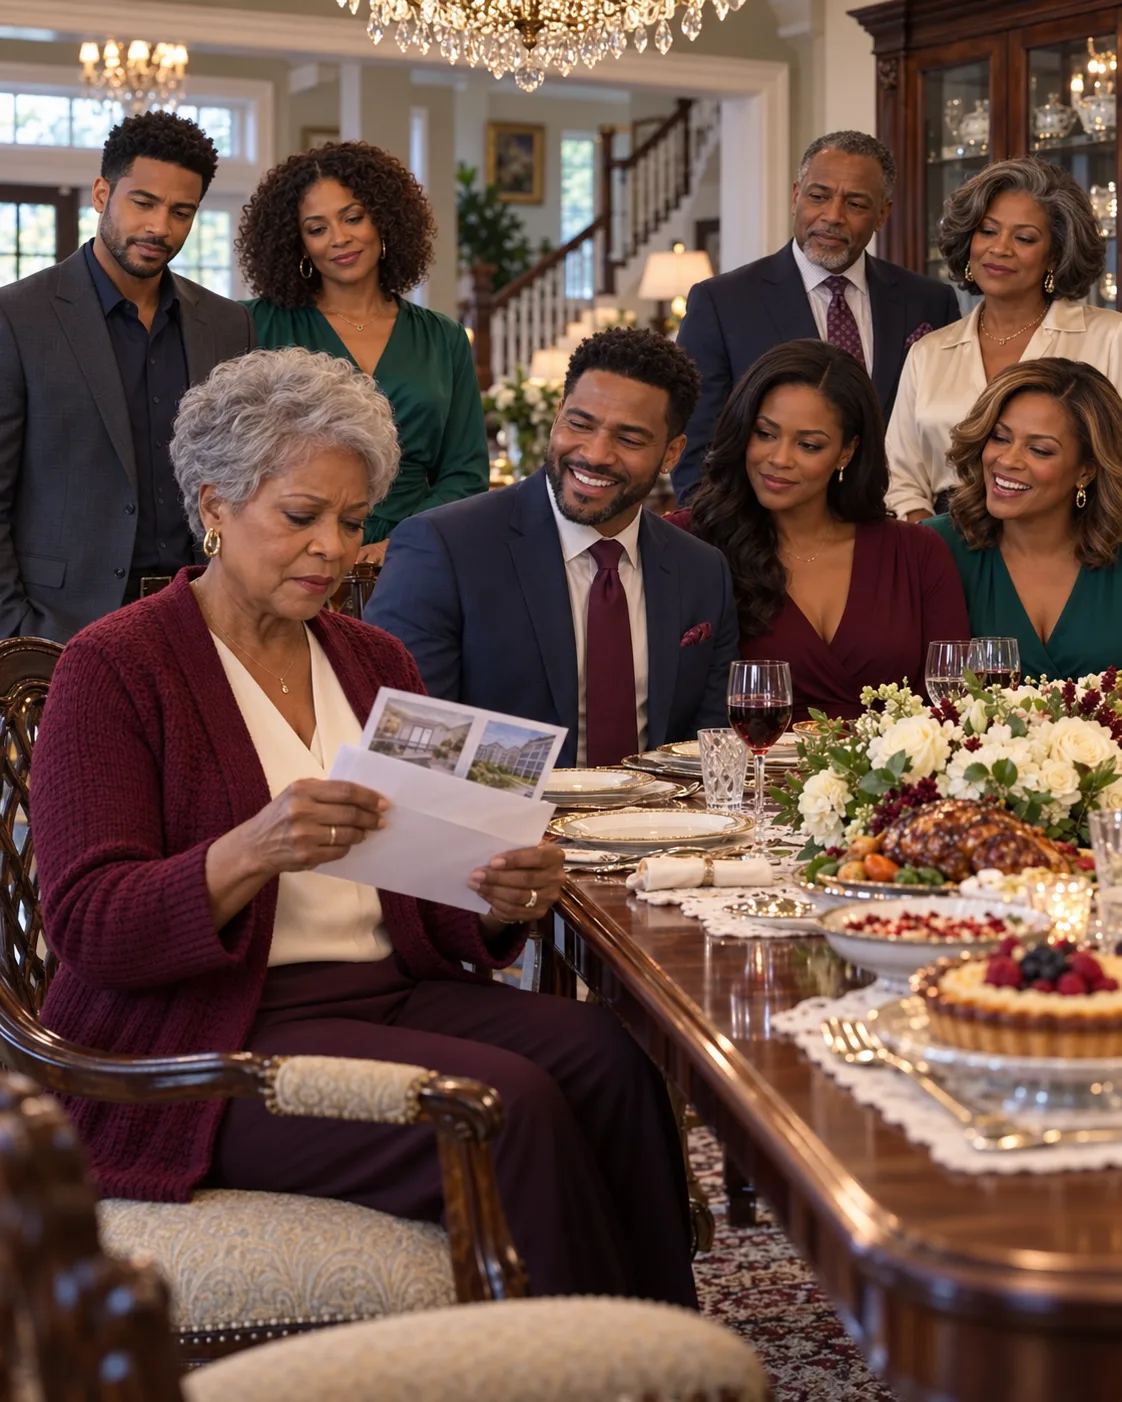
I set down my spoon.
“Nothing illegal.”
Marcus stared at me.
“That is not an answer.”
“It is the first answer you need.”
Vanessa moved closer to him.
“What did the bank say?”
He ignored her.
“Mom.”
I folded my napkin.
“The bank said exactly what I expected it to say.”
His face tightened.
Eight years earlier, when Marcus started Bennett Table & Event, the company had almost no borrowing history.
He had skill.
Clients.
Ambition.
A rented kitchen.
And not enough working capital to carry deposits, payroll, equipment purchases, and receivables between large events.
The bank liked the business plan.
It did not like the risk.
Henry had been dead less than a year.
Marcus came to me with a folder and said he needed one temporary favor.
A limited guaranty.
Not the house.
Not my retirement account.
A brokerage account Henry and I had built over thirty years.
I agreed to pledge a defined portion of that account as collateral support and sign a continuing guaranty capped at $300,000.
The documents were very clear.
My support covered existing obligations within the cap and future advances while the guaranty remained in effect.
I could revoke the guaranty for future advances by written notice.
Revocation would not erase money already borrowed.
It would not release collateral already supporting existing debt until the bank was satisfied.
And it would not force the bank to continue extending new credit once its support changed.
Marcus knew all of that.
At least he had known it when we signed.
Over the years, the company grew.
The bank renewed and expanded the revolving line.
Marcus became more successful.
My guaranty cap never increased.
My pledged account remained in place.
Every year, I received a notice.
Every year, I let it continue.
Not because Marcus could not function without me forever.
Because I thought family support was supposed to become quieter as the person no longer needed it.
Instead, my support became so quiet that Marcus forgot it existed.
Or pretended it did.
The night before, after everyone went to bed, I opened my desk.
I took out the original guaranty.
Read the revocation clause.
Then I wrote a short notice to the bank.
Effective upon receipt, I revoke my continuing guaranty solely as to future advances and decline any renewal or increase of my collateral support beyond obligations already outstanding.
I did not demand the bank seize anything.
I did not tell it to close Marcus’s company.
I did not withdraw pledged assets securing money already borrowed.
I exercised the exact contractual right the bank had given me eight years earlier.
At 7:11 that morning, I emailed the notice to the relationship manager and sent the signed copy through the bank’s secure portal.
At 8:03, he acknowledged receipt.
At 8:17, Marcus’s phone rang.
Now he stood in my kitchen looking as if I had pulled the foundation out from under him.
“You revoked the guaranty?”
“For future advances.”
“The bank froze the revolver.”
“The undrawn portion.”
“You know what that means.”
“I do.”
“We have payroll.”
“Then you need to speak to your banker.”
“You did this because of last night.”
“Yes.”
Vanessa gasped.
There was no reason to lie.
Marcus laughed once.
“You’re trying to destroy me because I asked you to move.”
“No.”
“You just cut off my company.”
“I stopped promising my assets for new borrowing by a company you call self-made.”
His face turned red.
“The business pays every bill in this house.”
I looked around my kitchen.
“No. The business pays some operating expenses for people who have been living in my paid-off house without rent.”
Vanessa stepped in.
“We pay taxes.”
“You pay the property tax bill because Marcus offered to take over the bill seven years ago.”
“That is still money.”
“Yes.”
I agreed because facts do not become false when spoken by someone who annoys you.
Marcus had paid taxes.
Utilities.
Groceries.
Landscaping.
Repairs.
That had real value.
So had eight years of rent-free occupancy in a five-bedroom house.
So had my $300,000 limited guaranty.
So had the pledged investment account that allowed his company to borrow at better terms than it otherwise could have obtained.
This was not a scoreboard yet.
It was simply the first time everyone was going to see the whole ledger.
Marcus grabbed his jacket.
“I have to fix this.”
“Yes.”
At the doorway he turned.
“You could have warned me.”
I almost smiled.
“You gave me a move-out date at dessert.”
Then he left.
Vanessa stayed.
For perhaps thirty seconds.
Then she looked at me and said:
“You’re enjoying this.”
I thought about it.
“No.”
That was true.
I was enjoying one thing.
Clarity.
Not fear.
Not payroll stress.
Not the possibility that employees who had nothing to do with our family might be affected.
I did not want Marcus’s company to fail.
I wanted my support to stop being invisible.
Vanessa said:
“If his employees lose their jobs—”
“They should not. The company has receivables, equipment, owners’ equity, and other financing options.”
“How do you know?”
“Because I read the annual statements before renewing support.”
Her mouth closed.
That was another thing they had never asked.
I knew exactly what I had guaranteed.
By lunchtime, Marcus’s banker called me directly.
Not to pressure me.
To confirm the notice.
I confirmed it.
He explained that because my guaranty and pledged securities were part of the borrowing base, the bank had suspended additional draws while credit reviewed replacement support.
The current outstanding balance—$214,600—remained outstanding under the existing terms.
No acceleration notice had been issued.
No demand for immediate payoff.
The company had thirty days under its documents to cure the collateral shortfall or negotiate a revised facility.
That mattered.
Marcus was not ruined.
He had a problem.
One I had stopped solving for him before he felt it.
At two that afternoon, I called my own lawyer.
Not the bank’s lawyer.
Not Marcus’s.
Rebecca Chen had handled Henry’s estate and several property matters for me.
I told her what happened.
Then I asked the question I should have asked years earlier.
“How do I make them leave my house legally?”
***
Rebecca did not say:
Change the locks.
She said:
“First, we determine what their occupancy is.”
Marcus and Vanessa had never signed a lease.
They did not pay fixed monthly rent.
But they had lived there for eight years, received mail there, paid household expenses, and treated the property as their primary residence.
Depending on state law and the facts, calling them “guests” would not make every occupancy rule disappear.
So we did it properly.
Rebecca reviewed the deed.
My name alone.
Henry and I had owned the property by the entirety.
After his death, title vested in me.
No transfer to Marcus.
No life estate.
No recorded interest.
No written promise that he would inherit the house.
Then she reviewed the expenses.
That was where my Sunday ledgers became useful.
Not glamorous.
Useful.
For eight years I had written down who paid what.
Property taxes.
Utilities.
Roof repair.
Boiler service.
Kitchen renovation.
Landscaping.
Insurance.
Groceries.
I had also recorded expenses Marcus never mentioned publicly.
The new roof five years earlier:
$31,800 from my savings.
Homeowners insurance:
paid by me every year.
Major boiler replacement:
$12,400 from my account.
Kitchen appliances Vanessa told people “we replaced”:
purchased by me.
The upstairs bathroom remodel:
Marcus paid $8,600.
The master-bedroom remodel:
Marcus and Vanessa paid most of it.
The property taxes over eight years were substantial.
So were the utilities.
Rebecca said:
“Do not minimize their contributions.”
“I won’t.”
“Also do not confuse contributions with title.”
“I won’t.”
Marcus’s attorney later argued he had an equitable claim for improvements and carrying costs.
That was not absurd.
People can have reimbursement arguments without owning property.
Rebecca’s response was simple.
Then account for both sides.
Fair rental value of the portion they occupied.
Payments they made.
Capital improvements.
Benefits received.
Any agreement about reimbursement.
No one got to choose only the numbers that made them generous.
We served a written termination notice consistent with the local occupancy rules Rebecca believed applied.
Sixty days.
Not the thirty-first.
The senior-living paper Marcus had handed me was meaningless because I had never signed it.
He had paid a reservation fee.
That was his problem.
I did not move.
I moved back upstairs.
That was the first practical fight.
Vanessa came home to find me standing in the master bedroom with two suitcases.
“What are you doing?”
“Sleeping in my room.”
“This is our room.”
“No.”
She stared at me.
“We renovated it.”
“You renovated a bedroom in my house with my permission.”
“You gave it to us.”
“I allowed you to use it.”
“That’s the same thing.”
“It isn’t.”
I did not throw their belongings outside.
I did not touch their clothes.
Rebecca had told me not to create unnecessary conflict while notice was running.
So I chose the second upstairs bedroom for myself instead.
Not because Vanessa was right.
Because winning every symbolic battle immediately was less important than ending the arrangement cleanly.
That lesson took maturity I did not feel.
Emily came over that evening.
She brought takeout.
No audience.
No speech.
Just noodles.
Then she put my ledger on the table.
“Can I ask something?”
“Yes.”
“How much have you actually helped Marcus?”
I showed her.
Not to turn her against him.
Because she had asked.
The original guaranty.
The brokerage pledge.
Two startup loans I had made to the business during its first eighteen months.
One for $40,000.
One for $25,000.
Both repaid with interest.
A delivery van Henry’s estate sold to Marcus below market value.
Three years of free use of my garage for inventory before the company leased a warehouse.
Emily sat very still.
“He calls himself self-made.”
“He did build the company.”
“That’s not what self-made means.”
I shrugged.
“Almost nobody is literally self-made.”
Marcus worked brutal hours.
Won clients.
Recovered from mistakes.
Hired people.
Took risks.
My support did not create every success.
His success did not erase my support.
Both were true.
That became the theme of the next two months.
Marcus found replacement financing.
Not overnight.
The bank reduced his available revolving line from $650,000 to $425,000 and required a higher interest margin because my collateral support was gone.
He and Vanessa contributed additional personal cash.
The company pledged two delivery vehicles and certain receivables.
Lucas, his minority business partner, signed a limited guaranty after independent counsel reviewed it.
Payroll went out on time.
No employee lost a job because I withdrew.
The company survived.
Marcus hated that I knew.
I hated that I was relieved.
Then something changed at Sunday dinner.
There was no Sunday dinner.
Vanessa stopped inviting people.
Marcus stopped performing generosity.
The house became quiet.
For eight years I had thought quiet would feel lonely.
It felt spacious.
There was another detail Rebecca insisted we handle carefully.
Marcus had paid the property taxes directly from his business account for several years.
That created two questions.
First, whether the company had properly treated those payments for tax and accounting purposes.
Second, whether Marcus had later started believing that paying a tax bill created ownership.
Those were not the same issue.
His accountant reviewed the books.
Some payments had been recorded as owner distributions to Marcus and then treated as personal household spending.
Others had been coded too loosely and required correcting entries.
No tax fraud scandal.
No secret lien on my house.
Just messy bookkeeping that had survived because nobody expected the family arrangement to be challenged.
Marcus hated the accountant’s conclusion.
“Paying the taxes didn’t count for anything?”
Rebecca answered:
“It counts as money you spent. It does not automatically become equity.”
That distinction became almost therapeutic.
Money can matter without becoming title.
Care can matter without becoming control.
A family contribution can be real and still have limits.
I wished we had said those things eight years earlier.
Then again, if we had, there probably would not have been a Sunday dinner with a senior-living lease hidden beside the pie.
***
The accounting meeting happened five weeks before their move-out date.
Marcus insisted.
His lawyer came.
Rebecca came.
Vanessa came.
I came.
Emily did not.
Good.
This was not a sibling tribunal.
Marcus placed a spreadsheet on the conference table.
Eight years of expenses.
Property taxes.
Utilities.
Groceries.
Landscaping.
Repairs.
Renovations.
His total was $286,400.
He looked at me.
“That is what I put into Mom’s house.”
Rebecca corrected him.
“That is what your spreadsheet says you spent while residing there. We still need to classify the items.”
Marcus leaned back.
“Fine.”
My side had its own schedule.
Estimated fair rental value for the spaces occupied by Marcus and Vanessa over eight years, adjusted conservatively and reduced for shared use.
Major capital expenses I paid.
Insurance.
Structural repairs.
Appliances.
Household costs.
And separate from the house:
the guaranty.
The pledged securities.
The early business loans.
Rebecca made sure we did not mash everything together.
Business support did not automatically offset residential expenses legally.
But it mattered to the family story.
For property settlement purposes, we focused narrowly on the house.
After documentation and negotiation, we agreed on something neither side loved.
Marcus would not pursue an ownership claim.
I would reimburse $18,500 for specific documented capital improvements that increased the house’s value beyond ordinary household use.
No reimbursement for groceries.
No reimbursement for routine utilities consumed while they lived there.
No reimbursement for property taxes beyond the negotiated accounting because their long-term rent-free occupancy provided substantial offsetting value.
No fictional eight-year rent bill.
No claim that they had lived free and contributed nothing.
The payment bought peace.
More importantly, the agreement stated clearly:
Marcus and Vanessa had no ownership interest in the property.
They would vacate by the agreed date.
They would remove their belongings.
They would not record any lien.
The locks would be changed afterward.
Marcus signed last.
Then he said:
“So after everything I paid, I leave with nothing.”
I looked at him.
“You leave with your marriage, your business, your vehicles, your retirement accounts, your possessions, and the benefit of eight years living in a house you did not own.”
His lawyer looked down.
Marcus said:
“You know what I mean.”
“Yes.”
He meant the house.
He had lived there long enough that expectation had hardened into inheritance.
I said:
“Did Gran leave it to you?”
“My grandmother has nothing to do with this.”
“Did your father leave it to you?”
“No.”
“Did I?”
His face tightened.
“No.”
“Then you are not losing it.”
That ended the conversation.
Vanessa moved out first.
Not dramatically.
She rented a townhouse closer to Marcus’s tasting space.
Three movers came on a Thursday.
I stayed home because I wanted to know what left.
Not to inspect every box.
To make sure heirlooms stayed.
Henry’s mother’s silverware almost went.
Vanessa had packed it with their dining things.
When I pointed it out, she froze.
“I thought it was ours.”
“No.”
She opened the box and handed it over.
No argument.
That moment summarized eight years better than any lawsuit could have.
They had not necessarily been plotting to steal from me.
They had simply stopped asking where my things ended and theirs began.
The crystal stayed too.
Their dishes left.
The expensive wine refrigerator Marcus bought left.
Good.
I hated that machine.
Marcus moved the following weekend.
The chair became the problem.
Henry’s chair.
The one Marcus had sat in when he told me to see how long I could manage without his money.
Two movers lifted it.
I said:
“That stays.”
Marcus looked at me.
“I had it reupholstered.”
“You paid to reupholster my chair.”
“You said I could use it.”
“I did.”
He laughed bitterly.
“Everything is yours.”
“No.”
I looked around.
“The things that are mine are mine.”
Different sentence.
Important difference.
He told the movers to leave it.
Then, before walking out, he stood in the kitchen.
The same place where the bank had called.
He said:
“You embarrassed me.”
“I did not tell anyone about the guaranty.”
“Emily knows.”
“She asked me directly.”
“You made me look like a liar.”
“No. Your story left out material facts.”
His jaw tightened.
“Same thing.”
“It isn’t.”
He left.
I changed the locks the next morning after the agreed surrender of possession.
Not before.
Then I sat in Henry’s chair.
It smelled faintly like Marcus’s cologne.
That annoyed me.
I opened the windows.
By evening, the house smelled like rain.
The move also exposed something about Vanessa.
She had spent years improving the house because she genuinely believed it would become theirs.
Not through fraud.
Through assumption.
She had saved paint swatches for the downstairs hallway.
Collected contractor quotes for finishing part of the basement.
Once, while packing, she showed me a folder labeled FUTURE HOUSE.
My address was written on the tab.
Inside were kitchen ideas, landscaping plans, even a sketch converting my downstairs guest room into a home office.
I looked at it for a long time.
“Did Marcus tell you I was leaving the house to him?”
She hesitated.
“He said it would make sense.”
“That is not the same thing.”
“I know that now.”
That folder explained some of her behavior without excusing it.
She had not thought she was displacing me from my own home.
She had gradually rewritten me as a temporary occupant of their future home.
That was almost worse.
Not malicious.
Erasing.
I told her:
“You never had to hate me to make me disappear.”
She cried.
I did not comfort her.
Not because I wanted her hurt.
Because some realizations belong to the person having them.
***
Living alone again was not instantly empowering.
That part surprised me.
The first week, I loved the quiet.
The second, I noticed every sound.
The refrigerator clicked.
Pipes settled.
Branches scraped the siding.
One night I woke convinced someone was in the kitchen.
Nobody was.
For eight years, there had always been footsteps.
Doors.
Television.
Vanessa on the phone.
Marcus coming home late.
I had wanted my house back.
I had forgotten that getting something back can include grief for what occupied it.
Not all of the eight years had been bad.
Vanessa once drove me to the emergency room when I had kidney stones.
Marcus replaced a flat tire in sleet.
We had Christmas mornings.
Birthday cakes.
Movie nights.
Arguments about thermostat settings that were actually funny before they became symbolic.
Entitlement had grown slowly inside ordinary family life.
That made it harder to sort.
I started therapy at sixty-six.
Emily laughed when I told her.
Not mockingly.
“Mom, I’ve been telling you for years.”
“You are very annoying.”
“Inherited.”
Fair.
The therapist asked why I had let Marcus take over so much.
The answer was not weakness.
At first, convenience.
Then gratitude.
Then grief.
After Henry died, decisions exhausted me.
If Marcus wanted to handle the property-tax payment, good.
If Vanessa wanted to plan Christmas dinner, good.
If they wanted the upstairs room, maybe I did not need it.
Every surrender reduced friction.
Until I no longer recognized the cumulative result.
My therapist said:
“Boundaries usually fail by inches before anyone notices the missing mile.”
I wrote that down.
Marcus and I did not speak for four months.
Emily saw him.
I never asked her to report.
That was important.
She loved her brother.
She loved me.
I did not want loyalty to become surveillance.
Then one afternoon Marcus called.
“Can I come by?”
“For what?”
“I want to talk.”
I almost said no.
Then:
“Sunday. Two o’clock. One hour.”
He arrived alone.
No tailored jacket.
No expensive wine.
He sat in a dining chair.
Not Henry’s.
Good instinct.
For a few minutes, we discussed nothing.
Then he said:
“The company almost failed in year two.”
“I know.”
He looked surprised.
“Dad told me.”
Henry had been alive during the first months of the business.
Marcus had not yet married Vanessa.
He once missed payroll projections badly enough that a client delay nearly created a crisis.
I had made the second $25,000 loan then.
Marcus said:
“I forgot how scared I was.”
“That happens.”
“No. I think I edited it.”
I waited.
He continued.
“I remember working eighteen-hour days. I remember selling my car. I remember landing the museum contract. I remember everything I did.”
He looked at me.
“I stopped remembering what anyone else did.”
There it was.
Not self-made as a lie.
Self-made as selective memory.
He said the banker had shown him the original credit memo during refinancing.
The memo described my guaranty as “material support enabling initial facility.”
Marcus had read it.
Then sat in his car and cried.
I did not say good.
He said:
“I thought paying bills here made us even.”
“Even with what?”
“Everything.”
That was the family disease.
Accounting where nobody agreed on categories.
He thought utilities repaid startup support.
I thought startup support was simply something parents did.
He thought property taxes created a claim on the house.
I thought eight years without rent balanced ordinary household contributions.
Neither of us had ever said any of it aloud.
Then he apologized.
Not for “how things came across.”
For trying to relocate me without asking whether I wanted to move.
For discussing my house with Vanessa as though ownership would naturally transfer to them.
For using the money he spent publicly to make me appear dependent.
For the line at dinner.
“Let’s see how long you last without my money.”
He looked sick repeating it.
I said:
“That line was useful.”
He blinked.
“It made me check the whole arrangement.”
“That doesn’t make it okay.”
“No.”
He asked whether I forgave him.
I said:
“I believe your apology.”
Different answer.
He nodded.
That was enough for that Sunday.
Therapy also made me examine my own relationship with being needed.
I had always thought Marcus was the one performing generosity.
True.
But I had my own quieter version.
I liked being the mother who could help.
The guaranty.
The startup loans.
The free garage.
Paying for family vacations after Henry died because I wanted everyone together.
I rarely attached conditions.
That sounded noble.
Sometimes it was avoidance.
If I never named the value of what I gave, I never had to risk hearing someone say no.
My therapist asked:
“Did Marcus know the guaranty was emotionally meaningful to you?”
“No.”
“Did you ever tell him you hoped he would eventually stop needing it?”
“No.”
“Then part of your resentment depended on him reading an expectation you never stated.”
I hated that.
It was also true.
His entitlement was his responsibility.
My silence was mine.
So when we began rebuilding contact, I changed one habit.
I stopped offering before people asked.
Emily needed a new roof?
I waited until she asked whether I knew a contractor.
Marcus mentioned equipment financing?
I listened.
Did not volunteer collateral.
At first, restraint felt ungenerous.
Then it felt respectful.
Adults deserve the chance to solve their own problems before someone with more resources turns help into the shape of the relationship.
***
Three years later, Marcus still runs Bennett Table & Event.
The company is smaller than he once wanted.
More profitable than it used to be.
He sold the downtown tasting space after realizing it was mostly vanity and rent.
The bank renewed his line without me.
No family collateral.
No family guaranty.
The interest rate was worse for a while.
Then improved after two strong years.
He stopped calling himself self-made.
Not because I demanded it.
Because one evening at a business award dinner, he thanked people.
Lucas.
His first chef.
The banker who took the original chance.
Henry.
Me.
He did not say I built the company.
I did not.
He said:
“My mother backed me before a bank had much reason to.”
Accurate.
That was enough.
Vanessa and I took longer.
She apologized almost a year after moving out.
Her first attempt was terrible.
“I’m sorry you felt pushed out.”
I looked at her.
She closed her eyes.
“Okay. I hear it.”
Good.
The second attempt came months later.
“I treated your house like our future asset instead of your current home.”
Much better.
She also admitted something I had not known.
The senior-living apartment had not been Marcus’s idea first.
It was hers.
She had toured it with her mother.
Paid the reservation fee from her own account.
Then sold Marcus on the idea by framing it as something “good for me.”
That hurt.
She did not blame Marcus.
He had agreed.
He had handed me the envelope.
Shared responsibility.
Vanessa and I are polite now.
Sometimes warm.
Never close.
That is acceptable.
Emily remains Emily.
She visits every Tuesday for coffee when work allows.
She still asks about the roses.
David fixes things I could pay someone to fix because he genuinely enjoys fixing them.
The difference is he asks first.
“Want me to take a look at that hinge?”
A small sentence.
A beautiful one.
The house changed.
I moved back into the upstairs master bedroom eighteen months after Marcus left.
Not immediately.
At first, I could not.
Vanessa’s wallpaper.
Their closets.
The light fixtures they chose.
Too much of their version of the room.
So I renovated it.
With my money.
My decisions.
Not back to Henry’s room.
That surprised me.
I chose pale blue walls instead of the cream he loved.
Changed the curtains.
Bought a reading chair.
Kept one photograph of him on the dresser.
Marriage had lasted thirty-eight years.
I did not need the room frozen at year thirty-eight to prove it.
Henry’s old chair stayed downstairs.
I had it cleaned.
Did not reupholster it.
The fabric Marcus chose was actually excellent.
I can admit that.
The household ledger changed too.
I still update it every Sunday.
Now the first page contains a note.
Contribution is not ownership.
Help is not authority.
Gratitude is not debt.
A little dramatic.
At sixty-nine, I allow myself.
The brokerage account that had supported Marcus’s business remained mine.
Once the bank released the final collateral hold after the refinancing, I moved part of it into a more conservative allocation with my financial adviser.
Not because Marcus frightened me away from risk.
Because my own needs changed.
I increased my long-term-care reserve.
Updated powers of attorney.
Changed emergency contacts.
Emily became primary financial agent if I lose capacity someday.
Marcus is successor.
Yes.
Successor.
Some people find that strange.
Trust can be damaged without becoming permanently impossible.
The documents include safeguards.
Independent accounting.
No self-dealing.
Required reporting to both children.
I learned.
So did he.
Two years after our fight, Marcus asked whether I would consider selling the house eventually.
My body tensed.
He noticed.
Then immediately said:
“Not to me. I mean because it is big.”
That was true.
Five bedrooms.
Stairs.
A yard I loved but might not always manage.
I said:
“Maybe.”
He nodded.
No brochure.
No move-in date selected for me.
No plan made in my absence.
That was progress.
I later toured two retirement communities myself.
Not because Marcus had been right to evict me.
Because someday I may want less house and more freedom.
One had terrible carpeting.
One had an excellent library.
I went home and wrote notes.
My choice.
That distinction changes everything.
The strangest moment came at my seventieth birthday.
Family dinner.
My house.
My guest list.
Marcus asked before sitting in Henry’s chair.
“Is this okay?”
I looked at him.
Then at the chair.
“Yes.”
He sat.
No symbolism required.
After dinner, he carried dishes into the kitchen.
Vanessa brought dessert.
Emily opened wine.
Nobody made a speech about taking care of me.
Thank God.
At one point Marcus reached for the thermostat.
Then stopped.
“Too warm?”
I smiled.
“Don’t touch it.”
He raised both hands.
Everyone laughed.
Including me.
The old sentence came back to me then.
Let’s see how long you can manage without my money.
The answer turned out to be:
Quite well.
But that was never the most important answer.
The more important one was that Marcus could manage without mine too.
His business did not collapse when my backing ended.
My life did not collapse when his bill payments stopped.
We had both confused financial entanglement with proof of love.
Untangling it hurt.
Then clarified.
When people hear the story, they like the bank call.
The smug son.
The quiet mother.
The frozen credit line.
It sounds like revenge.
It was not.
I did not take anything that belonged to Marcus.
I stopped extending something that belonged to me.
That is a different kind of power.
Less dramatic.
More durable.
My house remained mine because the deed said so.
My investments remained mine because the account said so.
My relationship with my son survived because, eventually, neither of us needed money to say what we meant.
And if I move someday, I will fold my own papers.
Choose my own date.
May you like
Carry my own key to whatever comes next.
No one will slide my future across a dessert table again.